# Collateral management in the euro area since the introduction of the Eurosystem Collateral Management System (ECMS)
* [*1 Introducing the ECMS*](#tar-1 "1 Introducing the ECMS")
* *[*2 The journey to the ECMS: harmonisation and innovation*](#tar-2 "2 The journey to the ECMS: harmonisation and innovation")*
* **[*AMI-SeCo harmonisation activities*](#tar-3 "AMI-SeCo harmonisation activities")**
* ***[*3 Advantages for collateral management through the ECMS*](#tar-4 "3 Advantages for collateral management through the ECMS")***
* ***[*4 Migration to the ECMS and initial post-launch assessment*](#tar-5 "4 Migration to the ECMS and initial post-launch assessment")***
* ***[*5 Outlook*](#tar-6 "5 Outlook")***
* ***[*List of references*](#tar-7 "List of references")***
****The Eurosystem Collateral Management System () was launched successfully on 16 June 2025. The will provide monetary policy counterparties with a single gateway for managing eligible assets across all central banks. This new system constitutes an integral part of Services. Provision of collateral is necessary because Eurosystem credit can only be granted against collateral. Prior to the introduction of the , collateral was managed through 20 different systems operated by the individual national central banks. Migrating to a unified system makes mobilising and managing collateral significantly more efficient and also delivers both economic and operational benefits, including for the Eurosystem. The is the final project to be completed as part of the Eurosystem's Vision 2020, which aims to upgrade and decisively enhance the Eurosystem's market infrastructure in the fields of payments and securities settlement. Notably, the also improves liquidity management for market participants by making it easier for them to mobilise cash, securities and collateral. Furthermore, it marks a significant step towards the savings and investments union, an initiative to integrate European financial markets.****{#par-a78673}
****The represents a technical upgrade of the national collateral management systems, offering counterparties a variety of new and enhanced functionalities. In addition, it further improves security, as the is accessed exclusively via one of the two Eurosystem-approved network service providers or the Eurosystem Single Market Infrastructure Gateway (). Moreover, the 's state-of-the-art technical design and adherence to the latest standards, such as the 20022 standard for messaging with users and other systems, will make it easier to efficiently upgrade and expand the system going forward. Future adjustments will also have to take account of the extent to which digital securities based on distributed ledger technology () can be used as collateral within the Eurosystem.****{#par-e33424}
****The Bundesbank provided close support to all of its monetary policy counterparties during the changeover to the to ensure that their migrations ran smoothly. As part of the migration process, collateral worth around €360 billion was transferred from the Bundesbank's previous collateral management system to the . Now that the has been launched, more than 140 counterparties in Germany are connected to the system directly and a further 515 are connected indirectly via third parties.****{#par-e8eiu2}
***1 Introducing the*** {#tar-1}
--------------------------------
*****The** **was launched successfully in June 2025.** This new system provides monetary policy counterparties with a single gateway for managing eligible assets across all central banks and constitutes an integral part of Services.[\[1\]](#_ftn_root_1) Article 18.1 of the Statute of the European System of Central Banks stipulates that Eurosystem credit operations must be based on the provision of adequate collateral.[\[2\]](#_ftn_root_2) In order to settle Eurosystem credit operations and efficiently manage eligible assets, high-performance technical systems are indispensable. Prior to the introduction of the , these assets were managed in a decentralised manner via the separate collateral management systems operated by each of the 20 Eurosystem national central banks () in accordance with the common provisions of the operational framework for implementing monetary policy. This meant that, even though the previous systems operated by the Bundesbank and the other conformed to a variety of common requirements, they nonetheless had considerable differences both technically as well as in terms of their interfaces and specific workflows. Mobilising collateral across national borders was also possible, but only by means of a technically complex procedure that required the central banks in question to enter into a correspondent banking relationship.[\[3\]](#_ftn_root_3)***{#par-oe91a3}
****The aim of the** **project was to create a unified collateral management system with fully harmonised functionalities.** The thus ensures that the assets used as collateral in Eurosystem credit operations are managed based on standardised processes across all of the countries in the euro area. In December 2017, the Governing Council of the European Central Bank gave its approval to start the realisation phase of the project, which went live on 16 June 2025. Upon its launch, the replaced the separate collateral management systems operated by the euro area . Above all, migrating to a unified system makes mobilising and managing collateral across national borders significantly more efficient.**{#par-u71a3e}
****The** **was developed as part of the Vision 2020 initiative.** This initiative had already delivered sweeping advances to market infrastructure in the areas of payments and securities settlement in the Eurosystem.[\[4\]](#_ftn_root_4) Specifically, the Eurosystem developed the Instant Payment Settlement () service, which went live in 2018, and also replaced the real-time gross settlement system with T2 in 2023, partly in an effort to optimise credit institutions' liquidity management for all Services (- consolidation). With the launch of the , the final project of Vision 2020 has been completed -- one that, through technical modernisation and other upgrades, ensures more efficient collateral management and settlement in the Eurosystem (see Chart 3.1). In conjunction with the other Services, the enables cash, securities and collateral to be mobilised smoothly throughout the Eurosystem.**{#par-i29894}
{#par-i69ea1}
**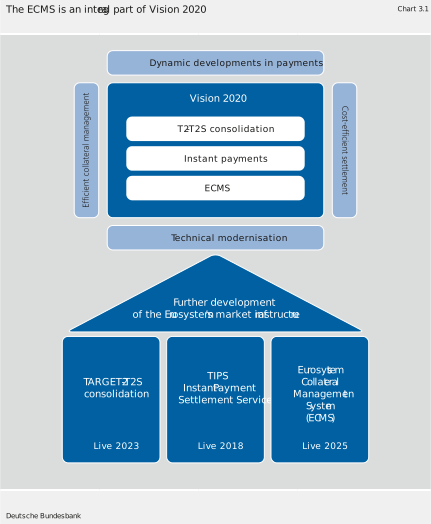**
***(Editor's note, correction to Chart 3.1 on 28 July 2025: In an earlier version of this chart, the live date for TARGET2-T2S consolidation was incorrectly stated as 2022.)***
****Collateral also plays a key role in the settlement of payments via central banks.** In March 2025, monetary policy counterparties in the Eurosystem pledged collateral worth more than €1,500 billion to cover credit risk in the event of the default of a counterparty to Eurosystem credit operations.[\[5\]](#_ftn_root_5) The Eurosystem is very demanding in terms of collateral quality and also applies various markdowns (haircuts) to the value of pledged collateral in order to account for market risk, amongst other things. Any collateral not reserved for refinancing operations can also be used for intraday credit operations in payments and, for example, to bridge temporary imbalances that might arise between monetary policy counterparties' incoming and outgoing payments during the course of a day. Any intraday credit operations that have not been repaid by the end of the day are automatically converted into overnight credit operations. In 2023, total secured intraday credit lines for payment purposes in came to between €1,400 billion and €2,000 billion,[\[6\]](#_ftn_root_6) though these only had to be used to a limited extent.**{#par-o27o17}
****The** **marks a significant step towards the savings and investments union.** The savings and investments union -- an initiative to deepen, integrate and enhance European financial markets -- will complement and continue the capital markets union project.[\[7\]](#_ftn_root_7) The overarching objective is to create a truly single market for capital across the in which finance can flow largely unimpeded between all Member States, thus opening up new sources of financing for firms and facilitating cross-border investment. In addition, the savings and investments union would thus also make the financial system more resilient as well as strengthen the euro's international role as an investment currency on a lasting basis. The supports the savings and investments union by making it easier and more efficient to make use of collateral across national borders and by helping to harmonise collateral management across the Member States of the Eurosystem. First, an asset's eligibility as collateral in central bank credit operations is a particular hallmark of its quality, given that it can be pledged as collateral to procure liquidity within the Eurosystem, if needed. Second, the marks a significant step towards comprehensive harmonisation of the collateral arrangements needed for a wide range of financial market operations, whether they are settled bilaterally or, for example, via central counterparties (such as margin calls for centrally cleared derivatives). A particular role in the area of collateral management is played by triparty collateral management services, which are collateral management systems provided externally by various market participants (triparty agents, or TPAs) that allow securities portfolios to be used flexibly for a variety of purposes (such as securities lending and money market transactions). The Eurosystem also accepts collateral provided via eligible TPAs such as Clearstream Banking Luxembourg with its CmaX service.[\[8\]](#_ftn_root_8)**{#par-u25541}
**2 The journey to the : harmonisation and innovation** {#tar-2}
----------------------------------------------------------------
****Harmonisation helps to overcome fragmentation in** **financial markets.** The Eurosystem has a substantial interest in promoting European financial integration and helping to forge a truly single market in this segment in Europe.[\[9\]](#_ftn_root_9) Harmonised procedures for managing collateral are key to creating a truly single market in the financial sector. However, in this regard, there are still significant barriers and impediments arising from fragmented national-based standards and differences in market practices.[\[10\]](#_ftn_root_10)**{#par-iu2536}
****In preparation for the** ,**the Eurosystem rolled out various collateral management harmonisation activities.** In an effort to overcome the existing fragmentation, the Eurosystem has, for some time now, also been looking to harmonise collateral management processes in Europe, and not just for its own purposes in the form of monetary policy collateral. The collateral management harmonisation process followed five guiding principles. First, harmonisation should lead to a single pan-European collateral management rulebook. This concerns the interaction between financial market infrastructures (for example, the central securities depositories required for securities safekeeping) and their users, which may include private financial institutions and also central banks. Second, harmonisation should implement messaging based on the latest international standards. Third, it should achieve interoperability. Fourth, it should allow for end-to-end automated processing. Fifth, it should remove operational restrictions that impede the availability, use and mobility of collateral. To achieve these goals, the Eurosystem's Advisory Group on Market Infrastructures for Securities and Collateral (‑SeCo), whose members include market participants from different countries, is working to develop a single collateral management rulebook for Europe ().[\[11\]](#_ftn_root_11) Looking ahead, the harmonised processes defined in the will make it significantly easier for market participants to mobilise their securities and collateral efficiently and safely throughout the euro area.**{#par-i8u569}
****The** **is the driving force behind various harmonisation activities.** The has identified a total of ten activities for which further harmonisation is urgently required (see the supplementary information entitled [MI-SeCo harmonisation activities](#AMI-SeCo-harmonisation-activities)). For three of these collateral management harmonisation activities (), standards have already been set out; these were implemented into the by the Eurosystem itself and went into effect on 16 June 2025. First, with regard to corporate actions for securities (a harmonisation activity that includes, for example, interest and redemption payments), an initial subset of harmonised workflows and messaging formats has been defined. Second, concerning billing processes, the has drawn up a single rulebook governing the fees incurred for the management of assets held as collateral. Third, agreement has been reached on a single triparty model for Europe that comprises harmonised processes for interaction amongst all key stakeholders.[\[12\]](#_ftn_root_12) Harmonisation activities in these three areas -- corporate actions, billing processes, and triparty collateral management -- include the use of messaging in accordance with the 20022 standard.[\[13\]](#_ftn_root_13)**{#par-aaau28}
**The standards for corporate actions, billing processes and triparty collateral management enable the Eurosystem to interact with all market participants using harmonised messaging formats and workflows. Implementation of these standards by market participants with direct interfaces to the was therefore a key prerequisite for the introduction of the . For this reason, the Eurosystem closely supported the market participants in question to help them prepare and implement their action plans. The remaining will be implemented at a later date. Overall, the Eurosystem has continuously monitored and communicated the progress made in implementing these standards in the respective markets, based on self-assessment in each case.[\[14\]](#_ftn_root_14)**{#par-u22ua1}
**harmonisation activities** {#tar-3}
-------------------------------------
### **Corporate actions**
**In general, a corporate action is an action or event decided by the issuer of a security which has an impact on the holders of that security. The standards developed for corporate actions ( ) Standards) cover three different areas: 1) processing of corporate actions on securities held in custody by intermediaries; 2) processing of corporate actions for bilateral collateral management, also involving Eurosystem central banks; 3) processing of corporate actions for triparty collateral management. The harmonisation also covers the use of 20022 messaging.**{#par-e22ae4}
### **Billing processes for fees**
**The Billing Processes Standards facilitate the management of fee invoices in connection with securities and collateral held at multiple central securities depositories (). These standards are intended to support the automation of billing processes through the inclusion of a minimum set of information in fee invoices. They also aim at aligning different billing dates. The information is to be sent via harmonised 20022 messages in accordance with a standard billing period. The Billing Processes Standards are aimed primarily at securities account servicers.**{#par-u7ue68}
### **Triparty collateral management**
**The harmonisation of the processes involved in triparty collateral management and in messaging seeks to standardise processes and thus facilitate the mobility of collateral between triparty agents. A single rulebook for processes has been developed which applies to both central banks and commercial banks. The implementation of triparty collateral management standards is mandatory for all triparty agents ( and large custodian banks).**{#par-io796e}
### **Taxation processes**
**The need to deal with different forms and procedures of taxation has been identified as an obstacle to the use of securities as collateral. Operational differences in the taxation procedures of individual euro area Member States make it more difficult to mobilise collateral and can therefore exacerbate collateral shortages. This is why the objective is to harmonise tax processing in the context of collateral management.**{#par-aae4i9}
### **Bilateral collateral management**
**Regarding bilateral collateral management, the agreed measures are aimed first and foremost at promoting more comprehensive automation of the main processes for non-cleared derivatives transactions, repurchase transactions (repos) and securities lending, in particular through the use of interoperable electronic platforms.**{#par-i232a3}
### **Margin calls**
**Margin calls arise when a counterparty's collateral pool is underfunded. In this case, the collateral providers (or borrowers) are obliged to offset this shortfall (margin) by providing additional collateral. In this respect, the objective is to create greater interoperability and leverage of existing infrastructures and market platforms for margin processes.**{#par-oa2371}
### **Cut-off times**
**Cut-off times concern, amongst other things, the mobilisation of collateral via links between international central securities depositories (). Minimum requirements for end-of-day cut-off times are intended to avoid different value dates in cross-infrastructure transactions in different markets, as this can lead to additional work for market participants.**{#par-a9852a}
### **Sourcing of collateral**
**The timely sourcing of collateral is essential for the efficient functioning of collateral management. A number of requirements have been defined with regard to aspects such as the maximum processing time for the submission of collateral. Harmonised minimum requirements for the sourcing and movement of collateral in the euro area are intended to significantly increase the efficiency of collateral management.**{#par-ia66oo}
### **Collateral dynamic and static data**
**In the past, up-to-date information (e.g. market value or eligibility) was sometimes only available to participants in certain markets. As a result, in other markets the collateral was not valued on the basis of correct information. The -SeCo is seeking to harmonise data exchanges and relevant market practices to ensure that up-to-date data are always available where necessary.**{#par-u724u2}
### **Non-euro collateral**
**The aim in this area is to harmonise different market practices for the handling of non-euro denominated collateral, including related corporate action processes. A further priority is interoperability between the two major , Clearstream Banking Luxembourg and Euroclear Bank (which together hold securities worth almost €20 trillion in their depositories), via the "Bridge" electronic communications platform.[\[1\]](#_ftn_4860a590_1)**{#par-u3o955}
1. **{#_ftn_4860a590_1} See Deutsche Bundesbank (2025c).**
****Further changes relating specifically to the Eurosystem's collateral management came into effect with the launch of the** . First, the national central banks in the euro area now only accept marketable assets from their monetary policy counterparties on accounts held at central securities depositories () that use the Eurosystem -Securities () platform to settle these transactions (" settlement policy").[\[15\]](#_ftn_root_15) This allows the to settle all securities transactions via a single interface to . As a result, interfaces to outside of are no longer necessary. It is likely that this will further strengthen as an integrated platform for securities settlement. Second, the makes it much easier to process the mobilisation of collateral across borders. Functionally, the correspondent central banking model () remains in place, but, for example, the fee previously charged for mobilising marketable assets via the no longer applies.[\[16\]](#_ftn_root_16) In addition, the cross-border use of collateral via the will also be possible in future using auto-collateralisation.[\[17\]](#_ftn_root_17) These changes make accessing collateral significantly easier for counterparties in all Member States of the Eurosystem. The harmonised processes and procedures for collateral management have been summarised by the Eurosystem in a guide on collateral management in Eurosystem credit operations.[\[18\]](#_ftn_root_18)**{#par-uu9eau}
**3 Advantages for collateral management through the** {#tar-4}
---------------------------------------------------------------
****As a single collateral management system, the** **offers a number of advantages.** The harmonises and consolidates collateral management in the Eurosystem. This brings advantages not only for market participants, but also for the Eurosystem. Overall, operating a single shared platform () is much more efficient than the individual central banks each operating their own separate platforms. The reduced complexity also makes it easier to maintain and develop shared applications. Better integration with Services and the use of joint components for certain functions also contribute to improved cost efficiency.**{#par-u95oe9}
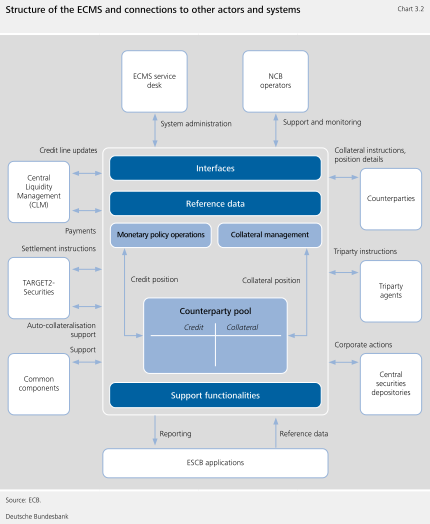
****The** **is essentially a common Eurosystem technical platform.** The business and legal relationships between the national central banks and their counterparties remain fundamentally unchanged. The national central banks also remain the points of contact for their monetary policy counterparties in all matters relating to collateral management. Within the , the national central banks maintain a collateral pool for each monetary policy counterparty to keep track of their collateral and credit positions. The reference data for this purpose come from the , triparty agents and databases of the European System of Central Banks with which the interacts, for example to valuate securities. Using this data, the calculates the free collateral value currently available for each counterparty and sends this information as a credit line[\[19\]](#_ftn_root_19) for intraday liquidity to the central liquidity management () of T2. Settlement instructions are sent to (see Chart 3.2).**{#par-u43oe9}
{#par-aui86o}
****
****The** **provides Eurosystem counterparties with a range of expanded, harmonised services for managing collateral in Eurosystem credit operations.** This is intended to ensure a level playing field for all counterparties and thus take account of the important principle of uniform implementation of monetary policy throughout the Eurosystem. For all counterparties, access is provided via a common interface that can be used across national borders. For banking groups participating in Eurosystem credit operations via multiple , the is likely to make group-wide collateral management significantly easier.**{#par-e4ai9o}
****The** **represents a technical upgrade of national collateral management systems.** For example, it offers additional functionalities such as setting a maximum credit line and, in the event of a shortfall in the collateral account, automatically mobilising cash collateral (i.e. using available account balances) and then releasing it as soon as a sufficient amount of other collateral is available. In addition, various counterparties belonging to a group can, for example, be placed together in a single banking group. One counterparty is then designated the "manager" of the banking group and is given access to a consolidated view of all collateral pools belonging to that group.**{#par-o72i7o}
****The** **has taken a number of measures to ensure a high level of security and future viability.** The can be accessed via one of the two Eurosystem-approved network service providers ( or Nexi-Colt) for Services. However, as a rule, counterparties that do not have their own contract with a network service provider have the option of using the network service provider of a third party. As with all other Services, participants can access the via , which allows for a high level of security.[\[20\]](#_ftn_root_20) Access can be either automated (application-to-application () mode) or manual (user-to-application () mode). access enables market participants' internal processing systems to interact directly with the via messages in accordance with the 20022 standard for the purposes of sending instructions or automatically receiving reports. This ensures the use of a common messaging standard. All communication between , triparty agents and the is carried out in mode. access enables counterparties to conduct screen-based online activities that are performed manually by the user via a graphical user interface. The 's modern technical design and adherence to the latest standards will also allow modifications and extensions to be implemented efficiently in the future.**{#par-e195u5}
**4 Migration to the and initial post-launch assessment** {#tar-5}
------------------------------------------------------------------
****In order to ensure smooth migration, the Bundesbank provided close support to all of its monetary policy counterparties during the changeover to the** . This support was guided by the Eurosystem's roadmap. The roadmap consisted of key milestones that were used to monitor the readiness levels of all institutions participating in the . To this end, the Bundesbank periodically surveyed all of its monetary policy counterparties on the extent to which they had reached the current milestones as well as their assessments of how they expected to reach future milestones. Their responses were factored into community readiness monitoring at the Eurosystem level. In support of this, various specialist training courses were offered to counterparties and relevant information was made available in a timely manner via the Bundesbank's website.**{#par-e28298}
****The** **launch and necessary migration activities were completed successfully.** From April 2023 to the end of May 2023, counterparties tested their connectivity in the pre-production environment. In August 2024, preparations for migration to the production environment began. The was scheduled to start operating in November 2024, but was ultimately launched in June 2025 to allow more time to ensure stability for its complex functionalities. Following the final migration preparations for all participants, a "big-bang" migration of every central bank took place between 13 and 15 June 2025. The first business day was thus 16 June 2025. As part of this successful migration, collateral worth around €360 billion was transferred from the Bundesbank's previous collateral management system to the . As of June 2025, more than 140 users in Germany were connected directly to the and a further 515 were connected indirectly via third parties.**{#par-e7u643}
**5 Outlook** {#tar-6}
----------------------
****Technological changes and market-driven innovations will continue to reshape collateral management in the Eurosystem over the next few years.** Following the successful launch, the objective for the coming months is now to ensure a high level of operational stability. At the same time, there will be a gradual rollout of a number of further improvements that could not be made available at launch due to reasons of prioritisation. Furthermore, the Eurosystem will closely monitor and analyse the changes in the collateral management landscape triggered by the . Account should also be taken of the fact that the environment surrounding collateral management is very dynamic. For example, it can be expected that the discussions on the savings and investments union will have implications for collateral management in the medium and longer term. This will hold particularly true if progress is made in further harmonising the regulatory framework for securities. In technical terms, the discussions on the use of in the securities domain will also require special attention. In 2024, the Eurosystem conducted an exploratory phase to test new technologies for the settlement of -based financial market transactions in central bank money.[\[21\]](#_ftn_root_21) Here, many market participants pointed out that eligibility plays an important role in the acceptance and prevalence of digital securities. In this respect, the Eurosystem will also have to clarify the extent to which such -based securities could be accepted and used as eligible collateral.**{#par-o2i124}
****List of references**** {#tar-7}
-----------------------------------
**Deutsche Bundesbank (2025a), [ECMS](https://www.bundesbank.de/content/723742).**{#par-oaueuu}
**Deutsche Bundesbank (2025b), [Mobilisation of collateral](https://www.bundesbank.de/content/625954).**{#par-ue4995}
**Deutsche Bundesbank (2025c), [Central securities depositories in Europe: sound foundations for the capital markets union](https://publikationen.bundesbank.de/content/952334), Monthly Report, March 2025.**{#par-uo6i73}
**Deutsche Bundesbank (2022), [Time for a genuine capital markets union](https://www.bundesbank.de/content/796818).**{#par-a39eu2}
**Deutsche Bundesbank (2015), [Bundesbank welcomes the creation of a Capital Markets Union](https://www.bundesbank.de/content/618552).**{#par-u3oa23}
**European Commission (2025), [Savings and Investment Union](https://ec.europa.eu/info/law/better-regulation/have-your-say/initiatives/14488-Savings-and-Investments-Union_en).**{#par-eu3e32}
**European Commission (2020), [A Capital Markets Union for people and businesses-new action plan](https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=COM:2020:590:FIN).**{#par-e3uo48}
**European Commission (2016), [Giovannini Reports](https://finance.ec.europa.eu/publications/giovannini-reports_en).**{#par-o9ie47}
**European Central Bank (2025a), [Eurosystem Collateral Data](https://www.ecb.europa.eu/mopo/coll/charts/html/index.en.html).**{#par-u64282}
**European Central Bank (2025b), [Eurosystem mission](https://www.ecb.europa.eu/ecb/orga/escb/eurosystem-mission/html/index.en.html).**{#par-u6oea6}
**European Central Bank (2025c), [SCoREBOARD: Tenth Compliance and Progress Report](https://www.ecb.europa.eu/press/intro/publications/pdf/ecb.amiseco202506_scoreboard.en.pdf?c612802a5ce143fabb044150aad78633).**{#par-i5oieo}
**European Central Bank (2025d), [The Eurosystem's exploratory work on new technologies for wholesale central bank money settlement](https://www.ecb.europa.eu/press/pubbydate/2025/html/ecb.exploratoryworknewtechnologies202506.de.html).**{#par-eu6ee7}
**European Central Bank (2024a), [Annual Report 2023](https://www.ecb.europa.eu/pub/targetar/html/ecb.targetar2023.en.html).**{#par-o12264}
**European Central Bank (2024b), [Collateral management](https://www.ecb.europa.eu/mopo/coll/coll/html/index.en.html).**{#par-e376u2}
**European Central Bank (2024c), [Collateral management in Eurosystem credit operations: Information for Eurosystem counterparties](https://www.ecb.europa.eu/pub/pdf/other/ecb.collateralmanagementeurosystemcreditoperations~cc619a1ab1.en.pdf).**{#par-i34225}
**European Central Bank (2024d), [Eurosystem Single Market Infrastructure Gateway User Detailed Functional Specifications](https://www.ecb.europa.eu/paym/target/consolidation/profuse/shared/pdf/ESMIG_UDFS_R2023.JUN_clean_20230303.en.pdf).**{#par-i4718u}
**European Central Bank (2019), [Collateral Management Harmonisation: Single Collateral Management Rulebook for Europe](https://www.ecb.europa.eu/paym/intro/publications/pdf/ecb.AMI-SeCo_Collateral_Management_Harmonisation.pdf).**{#par-eu7oee}
**European Central Bank (2015), [The future of Europe's financial market infrastructure: the Eurosystem's Vision 2020](https://www.ecb.europa.eu/press/key/date/2015/html/sp151014.en.html).**{#par-a31o42}
**European Central Bank (2004), [Institutional provisions: Statute of the and of the , Rules of Procedure](https://www.ecb.europa.eu/pub/pdf/other/ecbinstitutionalprovisions2004en.pdf).**{#par-e829o9}
**International Organization for Standardization (2024), [20022](https://www.iso20022.org).**{#par-i63435}
1. **{#_ftn_root_1} See Deutsche Bundesbank (2025a).**
2. **{#_ftn_root_2} See European Central Bank (2004).**
3. **{#_ftn_root_3} This is referred to as the "correspondent central bank model" (). Under the , a French bank, for example, would be able to pledge assets issued and held in custody in Germany to the Banque de France by means of an arrangement in which the Bundesbank would act as a correspondent central bank ().**
4. **{#_ftn_root_4} See European Central Bank (2015).**
5. **{#_ftn_root_5} See European Central Bank (2025a).**
6. **{#_ftn_root_6} See European Central Bank (2024a).**
7. **{#_ftn_root_7} See Deutsche Bundesbank (2015, 2022) and European Commission (2020, 2025).**
8. **{#_ftn_root_8} See Deutsche Bundesbank (2025b).**
9. **{#_ftn_root_9} See European Central Bank (2025b).**
10. **{#_ftn_root_10} See European Commission (2016).**
11. **{#_ftn_root_11} See European Central Bank (2019).**
12. **{#_ftn_root_12} In a triparty transaction, many of the collateral management tasks are outsourced to the triparty agent, while the legal relationship between the collateral giver and the collateral taker continues to exist.**
13. **{#_ftn_root_13} See International Organization for Standardization (2024).**
14. **{#_ftn_root_14} See European Central Bank (2025c).**
15. **{#_ftn_root_15}-Securities () is the Eurosystem's technical platform for harmonised and centralised securities settlement in central bank money. This is purely a settlement service that minimises risk in the post-trade domain through real-time settlement and shorter settlement chains. The safe custody of securities and the services this entails continue to be provided by the national .**
16. **{#_ftn_root_16} The correspondent central banking model () is a procedure developed by the Eurosystem central banks that enables credit institutions to provide collateral for monetary policy operations or payment settlement even if the collateral is held in another Member State of the euro area. The central bank of the country in which the collateral is held acts as the correspondent bank for the credit institution's central bank. See European Central Bank (2024b).**
17. **{#_ftn_root_17} Auto-collateralisation is intraday credit granted by a euro area national central bank in central bank money if a dedicated cash account () holder does not have sufficient funds to settle securities transactions; the collateral for this intraday credit is provided either through the purchased securities (collateral on flow) or through securities already held by the holder (collateral on stock).**
18. **{#_ftn_root_18} See European Central Bank (2024c).**
19. **{#_ftn_root_19} In order to avoid fluctuations in their credit lines, counterparties may, provided that they are authorised to do so, set a maximum credit line in the .**
20. **{#_ftn_root_20} See European Central Bank (2024d).**
21. **{#_ftn_root_21} See European Central Bank (2025d).**
*[TARGET]: Trans-European Automated Real-time Gross Settlement Express Transfer System
*[CSDs]: central securities depositories
*[NCBs]: national central banks
*[CLM]: central liquidity management
*[SWIFT]: Society for Worldwide Interbank Financial Telecommunication
*[**AMI-SeCo**]: Advisory Group on Market Infrastructures for Securities and Collateral
*[ICSDs]: international central securities depositories
*[DLT]: distributed ledger technology
*[ESMIG]: Eurosystem Single Market Infrastructure Gateway
*[A2A]: application-to-application
*[TARGET2]: Trans-European Automated Real-time Gross Settlement Express Transfer System 2
*[AMI]: Advisory Group on Market Infrastructures for Payments
*[CA]: certfication authority
*[TIPS]: TARGET Instant Payment Settlement
*[SCoRE]: Single Collateral Management Rulebook for Europe
*[CCB]: correspondent central bank
*[DCA]: dedicated cash account
*[ISO]: International Organization for Standardization
*[CMHAs]: collateral management harmonisation activities
*[U2A]: user to application
*[ECB]: European Central Bank
*[IT]: information technology
*[**EU**]: European Union
*[ESCB]: European System of Central Banks
*[EU]: European Union
*[AMI-SeCo]: Advisory Group on Market Infrastructures for Securities and Collateral
*[SSP]: Single Shared Platform
*[T2S]: TARGET2-Securities
*[CCBM]: correspondent central banking model
*[XML]: eXtensible Markup Language
*[OTC]: over-the-counter