# Public finances
* [*\[1\]*](#tar-1 "[1]")
* *[*1.1 Situation and outlook*](#tar-2 "1.1 Situation and outlook")*
* **[*The structural development of Germany's government finances in 2025*](#tar-3 "The structural development of Germany’s government finances in 2025")
* *[*1.2 Challenges for government finances*](#tar-4 "1.2 Challenges for government finances")***
* ***[*\[5\]*](#tar-5 "[5]")
* *[*2.1 2025 as a whole*](#tar-6 "2.1 2025 as a whole")*
* **[*2.2 Outlook for 2026*](#tar-7 "2.2 Outlook for 2026")*****
* ***[*3 Central government finances*](#tar-8 "3 Central government finances")
* *[*3.1 Annual accounts for 2025*](#tar-9 "3.1 Annual accounts for 2025")*
* **[*3.2 Outlook for 2026 and beyond*](#tar-10 "3.2 Outlook for 2026 and beyond")*****
* ***[*\[18\]*](#tar-11 "[18]")
* *[*4.1 Results for 2025*](#tar-12 "4.1 Results for 2025")*
* **[*4.2 Outlook for 2026 remains uncertain*](#tar-13 "4.2 Outlook for 2026 remains uncertain")*****
* ***[*5 Social security funds*](#tar-14 "5 Social security funds")
* *[*5.1 Pension insurance scheme*](#tar-15 "5.1 Pension insurance scheme")*
* **[*5.2 Federal Employment Agency*](#tar-16 "5.2 Federal Employment Agency")*****
* ***[*List of references*](#tar-17 "List of references")***
***1 General government budget [\[1\]](#_ftn_root_1)*** {#tar-1}
----------------------------------------------------------------
### **1.1 Situation and outlook** {#tar-2}
#### **1.1.1 Overview**
****Last year, the government deficit ratio stood at around 2½ %. The expansionary fiscal stance will now drive it steeply upwards. The debt ratio will thus also rise considerably.** The expansionary stance reflects strong growth in expenditure and -- to a much lesser extent -- tax cuts. It builds on a structural expenditure ratio of almost 50 %. Taxes and social contributions as a percentage of were approaching 42 % in structural terms in 2025. Despite tax cuts, there are no signs of this ratio falling substantially, as social contribution rates are likely to rise significantly. High deficits have also been fairly common in previous periods of upheaval and crisis. Targeted credit-financed measures can help to overcome such challenges. However, in order to keep the debt ratio under control, large deficits must not become entrenched.**{#par-ueio68}
{#par-a431ei}
****
#### **1.1.2 Results for 2025**
****Although the deficit ratio fell slightly to 2.4 % in 2025, according to the January data release, the structural budgetary position deteriorated slightly.** The deficit ratio decreased on balance due to the discontinuation of temporary crisis assistance measures (see the supplementary information entitled "[The structural development of Germany's government finances in 2025](#The-structural-development-of-Germany-s-government-finances-in-2025)"). On the revenue side, higher social contribution rates were also a factor. There were positive one-off tax developments on top of this. Expenditure also saw dynamic growth. Higher social security fund expenditure and increased spending on personnel stood out, partly owing to their relatively large share of total expenditure. Investment and interest expenditure likewise rose significantly.**{#par-ou5o97}
****The debt ratio stood at 63 % at the end of the third quarter of 2025 and is likely to have been similarly high at the end of the year.** It probably amounted to around 65 % at the end of 2025 when also including Germany's calculated shares in debt.[\[2\]](#_ftn_root_2)**{#par-oea1i5}
**The structural development of Germany's government finances in 2025** {#tar-3}
--------------------------------------------------------------------------------
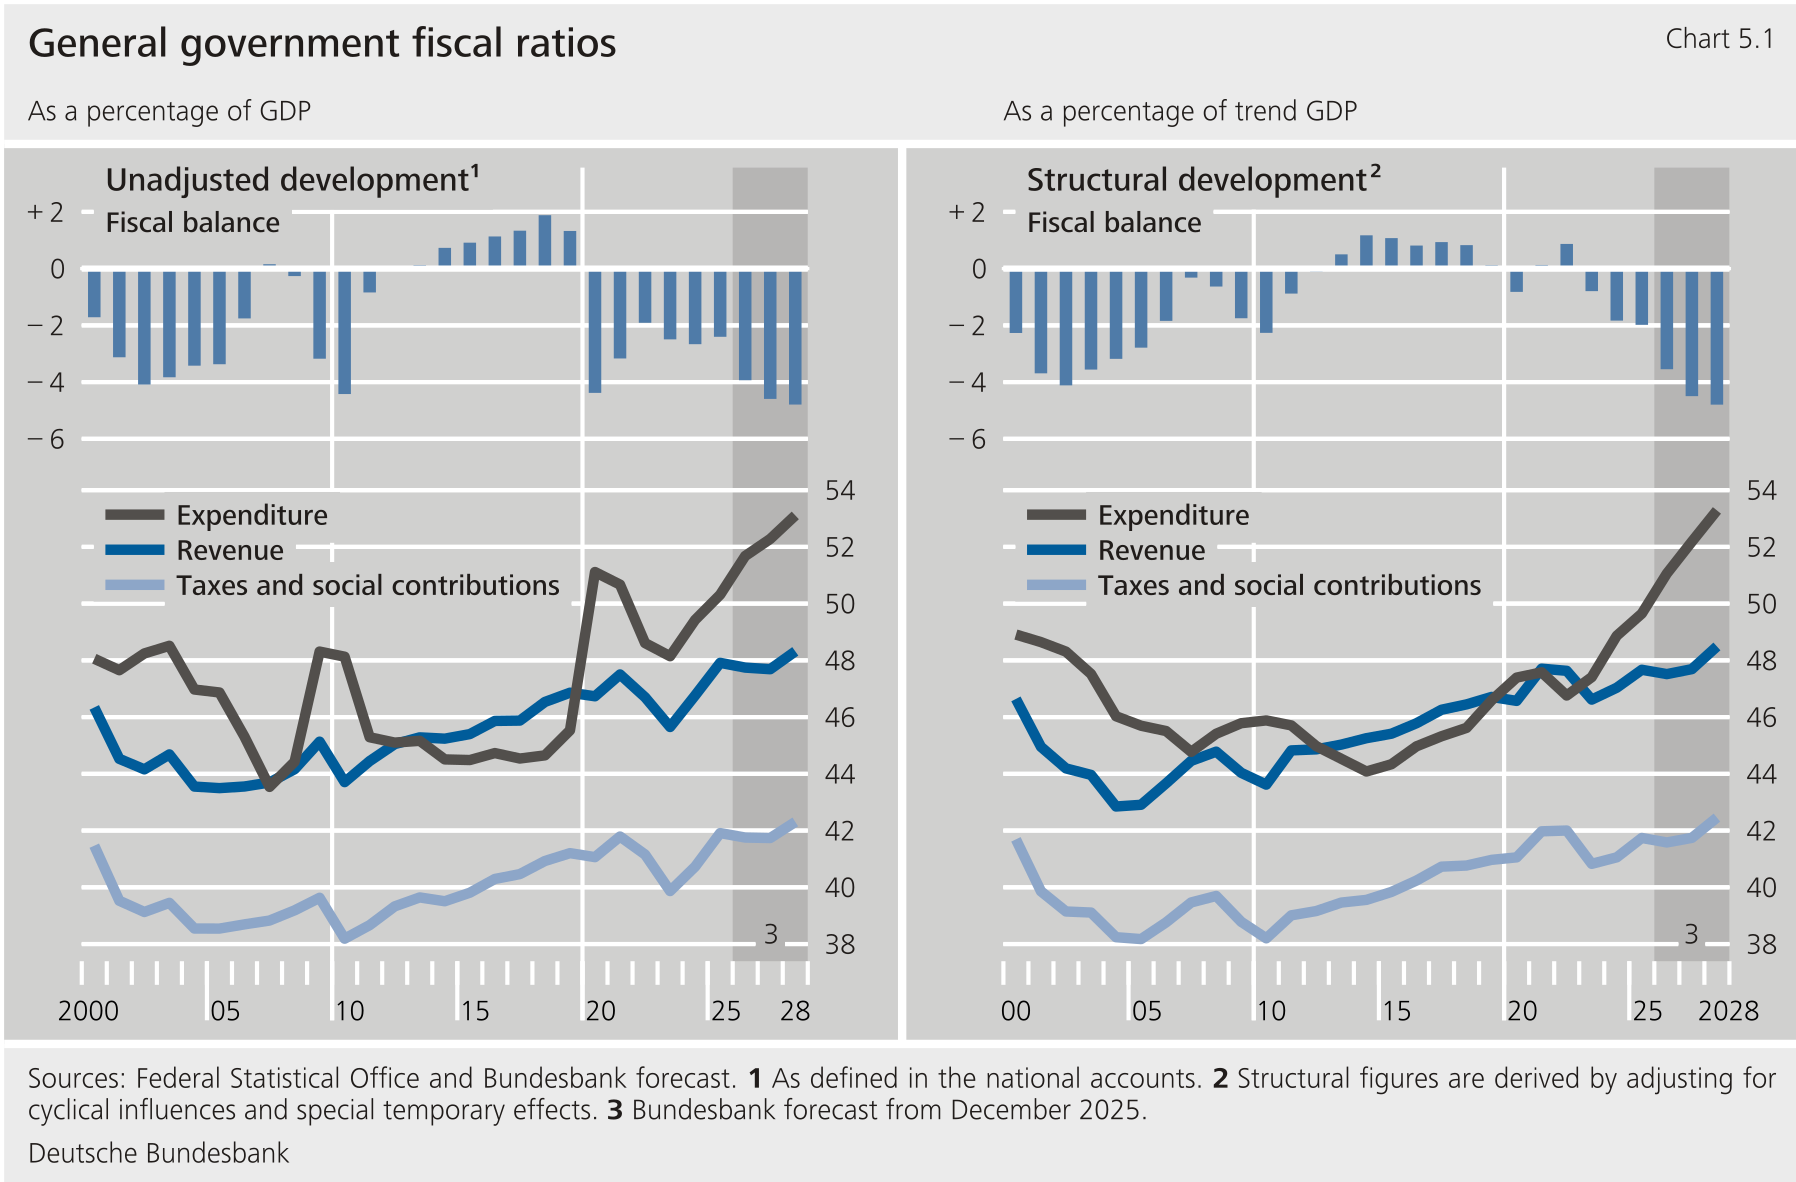
****According to the data reported in January, Germany's general government deficit stood at 2.4 % of** **in 2025. The ratio was down by 0.3 percentage point compared with 2024** (item 1 of Table 5.1).[\[1\]](#_ftn_45dfb2f5_1) This supplementary information analyses the reasons for this. To this end, temporary influences are identified. These are cyclical effects, temporary crisis response measures and other one-off effects. After factoring these out, structural developments are what remains.[\[2\]](#_ftn_45dfb2f5_2) The changes outlined below all compare 2025 with 2024. Chart 5.1 shows the longer-term changes in key general government fiscal ratios.**{#par-uo4862}
****Cyclical developments raised the deficit ratio slightly** (item 2). They mainly reduced revenue from profit-related taxes. At the same time, spending on unemployment rose. The cyclical burden remained limited, though. In particular, wages and salaries continued to see strong growth. Accordingly, wage tax and social contributions actually increased due to cyclical factors.**{#par-i9ua6a}
****However, the deficit shrank significantly due to the expiry of crisis response measures** (included in item 3). This alone caused the deficit ratio to fall by just over ½ percentage point. Most significantly, the practice of exempting certain wage components from tax and social contributions (inflation compensation bonuses) was discontinued at the end of 2024. In addition, the residual effects of the reduced rate on natural gas and district heating ceased. In the first quarter of 2024, the reduced rate introduced as a crisis response measure still applied.**{#par-e264u8}
****Another reason why the deficit fell in 2025 was a court decision that had a one-off negative effect on the budget in 2024** (included in item 3).[\[3\]](#_ftn_45dfb2f5_3) The repayment claims resulting from the decision were recorded in the national accounts in the year the decision was issued as a capital transfer amounting to ¼ % of . This transfer was a one-off, i.e. it was not made again in 2025.**{#par-iie8ae}
****On balance, the structural deficit ratio rose somewhat to 2 %** (item 4). The structural expenditure ratio (item 5 plus item 11) increased by slightly more than the structural revenue ratio (item 7).[\[4\]](#_ftn_45dfb2f5_4)**{#par-ae4o1i}
****One major reason for the increase in the structural expenditure ratio was higher social payments** (item 12). Expenditure on healthcare and long-term care, in particular, rose significantly. This was due not only to expanded benefits and higher prices but also to demographic developments. Pension spending likewise grew robustly. This was driven primarily by the large annual average pension increase and growing pension numbers. The public wage bill rose significantly because of higher compensation of employees (item 14). Interest expenditure increased due to growth in the average interest rate on government debt (item 5.1). In addition, the investment ratio rose slightly, primarily owing to higher expenditure on machinery and equipment (item 16).**{#par-i9a798}
****The structural revenue ratio increased mainly due to higher contribution rates to the social security funds** . The supplementary contribution rates levied by the health insurance institutions rose by an average of 1¼ percentage points. The contribution rate to the long-term care insurance scheme went up by ¼ percentage point. Due to higher contribution rates, revenue from social contributions rose faster than trend (item 9 and item 9.1). The tax ratio also went up (item 8). This was mainly because of one-off developments relating to withholding tax on interest income and capital gains as well as to inheritance tax (included in item 8 4).[\[5\]](#_ftn_45dfb2f5_5) Fiscal drag (item 8.1) and tax cuts (item 8.3) largely balanced each other out. Decoupling between the cyclically adjusted macroeconomic reference variables and developments (item 8.2) reduced the tax ratio slightly.**{#par-a86a9i}
****According to the structural ratios, there has not yet been any significant increase in infrastructure and defence spending.** Additional expenditure on infrastructure and defence (largely in the form of machinery and equipment purchases) ought to primarily increase the government structural investment ratio. This rose only slightly last year, by 0.1 percentage point. Defence spending affects other areas, such as intermediate inputs and personnel expenditure. In these areas, too, the higher cash outflows for defence spending had hardly any effect on structural ratios. Central government's new scope for borrowing (see item 2.f1 and item 3.c in Table 5.3 "Key central government budget data") has thus had little impact so far on structural spending on infrastructure and defence as defined in the national accounts.[\[6\]](#_ftn_45dfb2f5_6)**{#par-e63o5a}
{#par-a985u1}{#par-ooiau9}{#par-ou1o84}{#par-a61854}{#par-u87oa5}{#par-i2e51e}{#par-e4a3i5}{#par-eua634}{#par-ueui2e}{#par-o197o1}{#par-o418ii}{#par-o47882}{#par-ae9oo6}{#par-uu999e}{#par-u83u15}{#par-ia8ee4}{#par-ui2975}{#par-o58u55}{#par-ea7a9o}{#par-aieu17}{#par-i534ui}{#par-aoae14}{#par-i8ioee}{#par-e5a246}{#par-i46731}{#par-eou24i}{#par-ua91io}{#par-ao2a8u}{#par-e1e5e3}{#par-o95717}{#par-aoi575}{#par-uao854}
|---------|--------------------------------------------------------------|----------|----------|----------|----------|----------|----------|-----------------------------|
| **Table 5.1: Structural development of the government budget^\*^** Year-on-year change in the ratio to trend in percentage points |||||||||
| **Item** || **2020** | **2021** | **2022** | **2023** | **2024** | **2025** | **2025 compared with 2019** |
| **1** | **Unadjusted fiscal balance^1^** | − 5.7 | 1.2 | 1.3 | − 0.6 | − 0.2 | 0.3 | − 3.7 |
| **2** | **Cyclical component^1^** | − 2.1 | 0.6 | 0.4 | − 0.1 | − 0.1 | − 0.3 | − 1.6 |
| **3** | **Special temporary effects^1^** | − 2.7 | − 0.3 | 0.1 | 1.1 | 1.0 | 0.8 | 0.0 |
| **4** | **Fiscal balance** | − 0.9 | 0.9 | 0.7 | − 1.7 | − 1.0 | − 0.1 | − 2.1 |
| **5** | **Interest payable^2^** | − 0.2 | 0.0 | 0.1 | 0.2 | 0.2 | 0.1 | 0.3 |
| **5.1** | **due to change in average interest rate** | − 0.2 | − 0.1 | 0.1 | 0.2 | 0.2 | 0.1 | 0.3 |
| **5.2** | **due to change in debt level** | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| **6** | **Primary balance** | − 1.1 | 0.9 | 0.9 | − 1.5 | − 0.9 | − 0.1 | − 1.8 |
| **7** | **Revenue** | − 0.1 | 1.1 | − 0.1 | − 1.0 | 0.4 | 0.6 | 1.0 |
| **8** | **Taxes** | 0.2 | 0.7 | − 0.2 | − 1.4 | 0.0 | 0.2 | − 0.4 |
| **8.1** | **Fiscal drag^3^** | 0.1 | 0.1 | 0.2 | 0.3 | 0.2 | 0.2 | 1.1 |
| **8.2** | **Decoupling between macroeconomic reference variables and** | 0.0 | 0.0 | − 0.1 | − 0.1 | 0.0 | − 0.1 | − 0.3 |
| **8.3** | **Legislative changes** | − 0.2 | − 0.7 | − 0.7 | − 0.6 | − 0.2 | − 0.2 | − 2.6 |
| **8.4** | **Residual** | 0.2 | 1.3 | 0.4 | − 0.9 | 0.1 | 0.3 | − 1.4 |
| **9** | **Social contributions** | − 0.1 | 0.2 | 0.2 | 0.2 | 0.2 | 0.5 | 1.2 |
| **9.1** | **Contribution rate changes** | 0.0 | 0.1 | 0.0 | 0.2 | 0.2 | 0.6 | 1.2 |
| **9.2** | **Other** | − 0.1 | 0.1 | 0.2 | 0.0 | 0.0 | − 0.1 | 0.0 |
| **10** | **Other revenue^4^** | − 0.2 | 0.2 | − 0.1 | 0.2 | 0.2 | − 0.1 | 0.2 |
| **11** | **Primary expenditure** | 1.0 | 0.2 | − 0.9 | 0.5 | 1.3 | 0.7 | 2.8 |
| **12** | **Social payments** | 0.1 | 0.4 | − 0.4 | − 0.3 | 0.9 | 0.4 | 1.1 |
| **13** | **Subsidies** | 0.4 | − 0.4 | − 0.5 | 0.3 | 0.1 | − 0.1 | − 0.3 |
| **14** | **Compensation of employees** | 0.1 | 0.0 | − 0.2 | − 0.1 | 0.1 | 0.3 | 0.2 |
| **15** | **Intermediate consumption** | 0.2 | − 0.1 | 0.0 | 0.5 | 0.1 | 0.0 | 0.6 |
| **16** | **Gross fixed capital formation** | 0.2 | − 0.1 | 0.0 | 0.0 | 0.1 | 0.1 | 0.4 |
| **17** | **Capital transfers** | 0.0 | 0.2 | 0.3 | 0.3 | 0.0 | 0.0 | 0.8 |
| **18** | **Other expenditure^5^** | 0.1 | 0.2 | − 0.1 | − 0.2 | − 0.1 | − 0.1 | − 0.2 |
| *Memo items:* || |||||||
| **19** | **Real trend** **^6^** | 0.8 | 0.7 | 0.6 | 0.6 | 0.5 | 0.5 | 3.8 |
| **20** | **deflator^6^** | 1.8 | 2.7 | 6.4 | 6.7 | 3.1 | 3.0 | 26.1 |
| **\*** The structural figures are derived by adjusting for cyclical influences and special temporary effects. **1** Change in the ratio to compared with previous year. **2** 2025 breakdown estimated as end-year debt level is not yet available. **3** The term "fiscal drag" encompasses the positive revenue effect of bracket creep in income taxation and the negative impact of the fact that specific excise duties are largely independent of prices. **4** Other current transfers receivable, sales and total capital revenue (excluding capital taxes). **5** Other current transfers payable, other net acquisitions of non-financial assets. **6** Year-on-year percentage change. |||||||||
{#par-o5e2ue}
1. **{#_ftn_45dfb2f5_1} The table shows structural developments in the general government budget since 2020. The text explains what changed in 2025 compared with 2024.**
{#par-uo7ei3}
2. **{#_ftn_45dfb2f5_2} The Bundesbank uses its own estimation techniques (see Deutsche Bundesbank (2006)). Temporary and structural developments may therefore differ from those published by other institutions.**
{#par-i816o1}
3. **{#_ftn_45dfb2f5_3} In March 2024, the Federal Fiscal Court ruled that the capital gains tax paid by foreign investment funds that invested in German enterprises must be reimbursed.**
{#par-aoe9iu}
4. **{#_ftn_45dfb2f5_4} Here and in the remainder of the supplementary information, all statements refer to structural developments.**
{#par-a423ei}
5. **{#_ftn_45dfb2f5_5} See "[2.1 2025 as a whole](#2.1-2025-as-a-whole)".**
{#par-oo4eu4}
6. **{#_ftn_45dfb2f5_6} For more information on the differences between government investment in the government finance statistics and the national accounts, see Deutsche Bundesbank (2026), Annex ["In-depth analysis 1: How government investment and government capital stock are recorded in the statistics"](https://publikationen.bundesbank.de/publikationen-en/reports-studies/monthly-reports/monthly-report-january-2026-969030?article=government-investment-gear-new-scope-for-borrowing-towards-infrastructure-972822%231-In-depth-analysis-1-How-government-investment-and-government-capital-stock-are-recorded-in-the-statistics).**
{#par-eu9967}
#### **1.1.3 Outlook up to 2028**
****Over the course of this year and the next, the relaxed spending stance will cause the deficit and debt ratios to rise significantly.** The Bundesbank expects a deficit ratio of approximately 4 % in 2026 and around 4½ % in 2027. At the central government level, higher defence spending will contribute to the growing deficit. Furthermore, central, state and local government as a whole will see additional investment in infrastructure as well as rising interest expenditure and tax relief. A growing deficit is also expected for the social security funds in 2026 and 2027. This is because expenditure on pensions, healthcare and long-term care will continue to rise significantly more strongly than earnings subject to compulsory contributions. At the same time, contribution rates are likely to be raised only moderately in these two years, as the pension insurance scheme will probably be able to finance its steeply increasing deficit from its reserves until the end of 2027. In addition, central government will temporarily be extending loans to the Federal Employment Agency, the long-term care insurance scheme and the health insurance scheme in order to avoid stronger deficit increases in those areas.**{#par-iuaui8}
****Without a change in course, the deficit ratio will keep rising towards 5 % in 2028. In particular, government expenditure will continue to climb steeply, and enterprises will receive some further tax relief.** However, the deficit in the social security funds is likely to fall: The pension insurance scheme will then no longer be able to finance its financing gap solely from its reserves. Its contribution rate will therefore have to be raised sharply (see Chapter 5.1.3 "[Longer-term development and the Pension Commission](#5.1.3-Longer-term-developments-and-the-Pension-Commission)"). In the absence of measures to curb expenditure in the social security funds, the overall contribution rate could rise to 44½ % by 2028 (2025: 42½ %).**{#par-i2e133}
****The Federal Government's plans provide for central government addressing the steep increase in consolidation that is required to comply with the debt brake.**The national fiscal rules permit unlimited debt financing by central government to cover rising defence spending. In addition to this, the Infrastructure and Climate Neutrality Fund has large scope for borrowing. Nevertheless, unless countermeasures are taken, central government will significantly exceed its standard borrowing limit from 2028 onwards. This is due, amongst other things, to sharply rising interest expenditure and grants to the pension insurance scheme. At the same time, tax revenue growth will be fairly weak, not least owing to tax cuts. Furthermore, there will be no more available reserves in the core budget by then. The Federal Government closed the financing gap in its medium-term plan from summer 2025 by budgeting for non-specific global spending cuts. The Bundesbank's forecast does not include these savings, as its forecast generally only includes measures that have already been specified.**{#par-i95323}
### **1.2 Challenges for government finances** {#tar-4}
****Where intended to swiftly overcome challenges in defence and infrastructure, temporarily higher deficits are acceptable.** There needs to be a reliable way forward with regard to bringing the high deficits back down, and a targeted focus on the challenges ahead. According to the results and plans, debt financing obtained under the expanded borrowing limits is not currently accompanied by equally increased spending on defence and infrastructure (see Chapter 3 "[Central government finances](#3-Central-government-finances)" for more on this).**{#par-a676oo}
****The Bundesbank has submitted proposals to make more targeted use of the expanded scope for borrowing and to reliably safeguard sound government finances.** [\[3\]](#_ftn_root_3)The forthcoming budget and fiscal plans and the planned reform of the debt brake present opportunities for this. In addition, state governments are faced with the task of ensuring, via effective budgetary oversight and reasonable appropriations, that local governments reduce their large deficits and that cash advances do not sharply increase again.[\[4\]](#_ftn_root_4) In the case of the pension, health and long-term care insurance schemes, it will be important for the upcoming reforms to rein in expenditure (see Chapter 5.1.3 "[Longer-term development and the Pension Commission](#5.1.3-Longer-term-developments-and-the-Pension-Commission)" for more information on the pension insurance scheme), as levies on labour in Germany are already relatively high. Shifting burdens to the central government budget would add to the consolidation needs there. Central government still needs to sustainably counterfinance the December 2025 pension package, amongst other things. In view of demographic developments and the need for improvement in terms of defence and infrastructure, there is no doubt that the pressure on government finances is high. That being said, sound government finances are and will remain an essential basis for sustainable economic growth and reliable social systems.**{#par-a3u6i4}
**2 Tax revenue [\[5\]](#_ftn_root_5)** {#tar-5}
------------------------------------------------
### **2.1 2025 as a whole** {#tar-6}
****Tax revenue rose by a substantial 4½ % (+ €41 billion) in 2025, partly owing to positive one-off developments.** This growth was higher than had been anticipated on the basis of key macroeconomic reference variables,[\[6\]](#_ftn_root_6) fiscal drag and tax law amendments.[\[7\]](#_ftn_root_7) This was due, amongst other things, to the fact that taxable wage elements replaced tax-free inflation compensation bonuses paid out in the previous year. High growth in receipts from withholding tax on interest income and capital gains as well from inheritance tax also boosted tax growth significantly, probably for the most part temporarily.**{#par-o27o4o}
{#par-e29o68}
**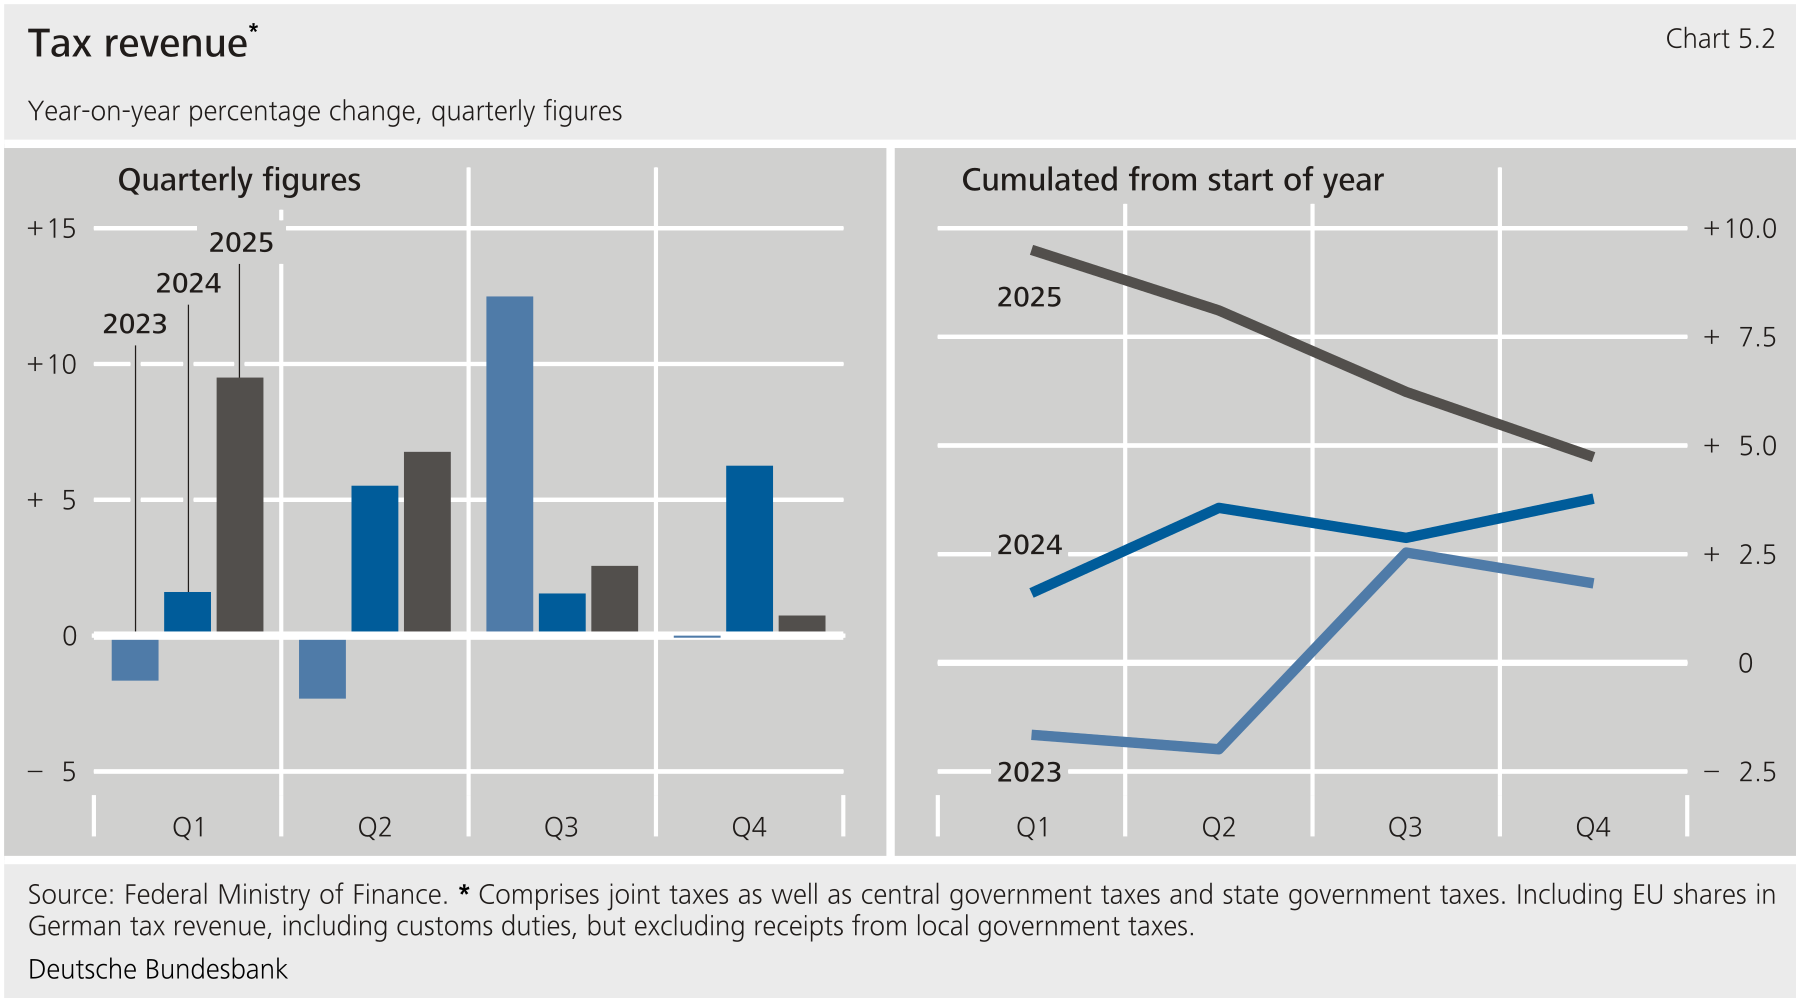**
****Tax revenue thus remained slightly below the official tax estimate of October 2025 (− €2 billion)** (see Chart 5.2 and Table 5.2). **However, the downward revision could be even smaller owing to local government taxes, which have been unexpectedly positive to date.** The deviation is attributable, in particular, to lower revenue from assessed income tax and . In the case of local business tax, by contrast, there have been signs of a small upward revision thus far.[\[8\]](#_ftn_root_8)**{#par-uo1e3e}
{#par-u84i76}{#par-e8181a}{#par-oi57ue}{#par-ao5ue3}{#par-eeu7i9}{#par-e4u1i5}{#par-a3oe28}{#par-iuo62o}{#par-eo5u8u}{#par-i1o589}{#par-iu9u58}{#par-uio57i}{#par-o3i41i}{#par-i22o52}{#par-ieau26}{#par-i317u5}
| **Table 5.2: Tax revenue** ||||||||||
| Type of tax | Year as a whole |||| Estimate for 2025^1^ | ||||
| Type of tax | 2024 | 2025 ||| Estimate for 2025^1^ | 2024 | 2025 |||
| Type of tax | € billion || Year-on-year change || Year-on-year change | € billion || Year-on-year change ||
| Type of tax | € billion || € billion | % | % | € billion || € billion | % |
| Tax revenue | |||||||||
| Total^2^ | 861.1 | 901.9 | + 40.7 | + 4.7 | + 5.0 | 235.1 | 236.9 | + 1.7 | + 0.7 |
| of which: | |||||||||
| Wage tax³ | 248.9 | 262.7 | + 13.8 | + 5.5 | + 5.3 | 69.1 | 72.7 | + 3.6 | + 5.2 |
| Profit-related taxes | 167.9 | 173.4 | + 5.6 | + 3.3 | + 3.9 | 45.3 | 42.9 | − 2.4 | − 5.3 |
| Assessed income tax^4^ | 74.8 | 78.4 | + 3.5 | + 4.7 | + 6.1 | 22.1 | 21.5 | − 0.6 | − 2.8 |
| Corporation tax^5^ | 39.8 | 39.2 | − 0.6 | − 1.5 | − 1.9 | 10.6 | 9.7 | − 0.8 | − 7.9 |
| Non-assessed taxes on earnings | 34.0 | 31.1 | − 2.9 | − 8.5 | − 6.4 | 7.3 | 5.9 | − 1.4 | − 19.1 |
| Withholding tax on interest income and capital gains | 19.3 | 24.8 | + 5.5 | + 28.7 | + 25.6 | 5.3 | 5.7 | + 0.4 | + 7.9 |
| ^6^ | 302.1 | 310.2 | + 8.1 | + 2.7 | + 3.0 | 80.9 | 78.8 | − 2.1 | − 2.5 |
| Other consumption-related taxes^7,8^ | 92.7 | 99.6 | + 6.8 | + 7.4 | + 8.1 | 26.2 | 27.8 | + 1.6 | + 6.2 |
|------------------------------------------------------|------:|------:|-----------|---------|----------------------|------:|------:|-----------|---------|
{#par-i81475}
### **2.2 Outlook for 2026** {#tar-7}
****Based on the most recent tax estimate and the legislative changes adopted** **in the meantime, tax growth of 2 % is expected for the current year.**[\[9\]](#_ftn_root_9)The recently adopted tax cuts will reduce growth by just over ½ percentage point. At the turn of the year, federal legislators reduced the rate on meals in restaurants. In addition, energy-intensive enterprises and the agriculture sector continue to pay a low rate of electricity tax. The standard mileage allowance for income tax purposes was expanded, and labour income earned beyond retirement age will also be exempt from income tax by up to €24,000 per year ("active pension"). None of these new measures had been taken into account yet in the last tax estimate. Stronger developments in the particularly relevant nominal tax reference variables could have a countervailing effect. This is indicated by the revisions in the Federal Government's Annual Economic Report 2026 relative to its 2025 autumn projection.**{#par-o557u4}
**3 Central government finances** {#tar-8}
------------------------------------------
### **3.1 Annual accounts for 2025** {#tar-9}
****Central government finances (core budgets and off-budget entities) closed the year with a steeply increased deficit of €84 billion** (2024: €49 billion). The increase solely concerned the core budget. Adjusted for financial transactions, the deficit grew significantly less (by €19 billion); see Table 5.3, item 1.e. This is because financial transactions depressed the deficit by €14 billion in 2024, but raised it slightly in 2025.**{#par-o17251}
****Core budget in a year-on-year comparison****{#par-i469o7}
{#par-e86eo3}
**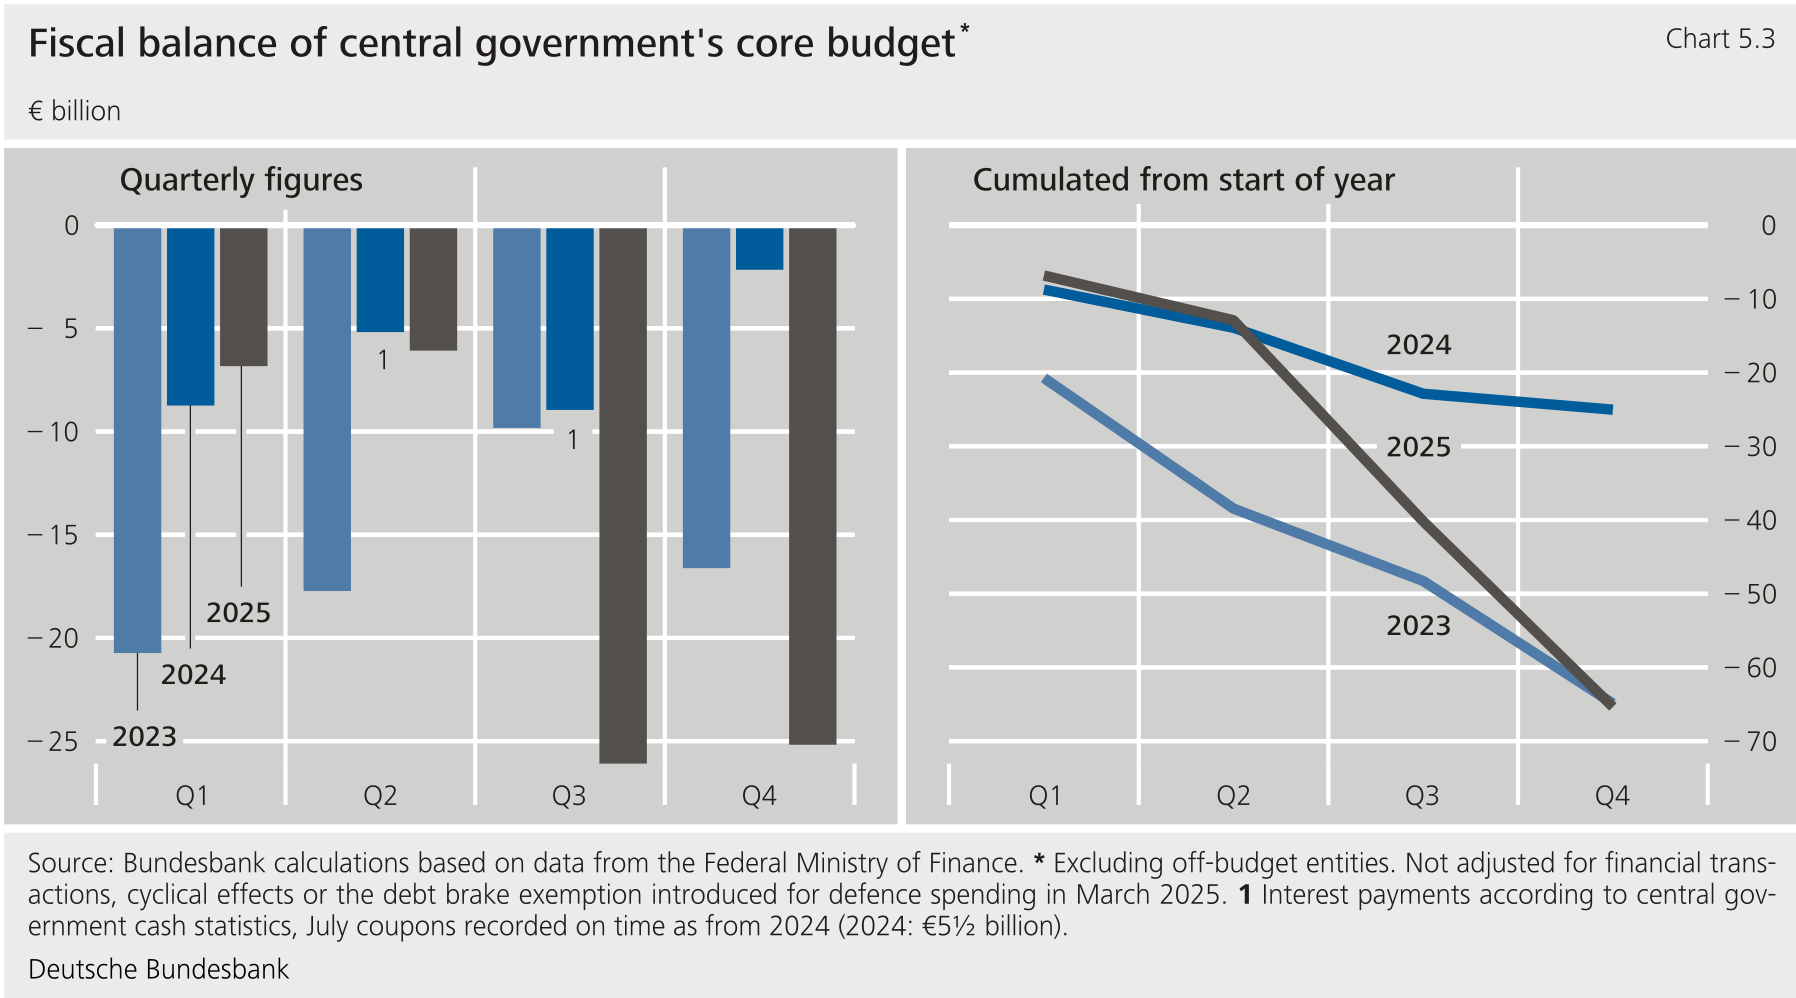**
****In the core budget, the deficit increased by €40 billion to €65 billion. Revenue fell by 2½ % and expenditure rose by 6 %.** Central government taxes saw growth of 3½ %, but there was no one-off revenue as in the previous year. First, central government received no payments from the 's programme; in 2024, these had amounted to almost €14 billion. Second, repayments of crisis assistance transfers to central government were lower (− €7 billion).[\[10\]](#_ftn_root_10) Third, the core budget had assumed the reserves of the Digitalisation Fund when central government dissolved it in 2024 (− €4 billion). Fourth, proceeds from sales of shares fell (− €3½ billion).**{#par-i4e178}
**Total expenditure rose, in particular, due to green electricity subsidies (just over €16 billion). In the previous year, this had been financed by an off-budget entity (the Climate Fund). Spending on the acquisition of financial assets (financial transactions) grew by just over €10 billion. Specifically, Deutsche Bahn received a significantly expanded capital injection as well as central government loans for more favourable refinancing terms on its capital market debt. Additionally, in contrast to previous years, central government granted loans to the Federal Employment Agency, the statutory health insurance scheme and long-term care insurance scheme (totalling just over €4 billion). Defence expenditure (i.e. spending allocated to the Ministry of Defence) increased by €9 billion. Furthermore, central government paid out an additional €6½ billion in grants to the statutory pension insurance scheme. On the other hand, investment expenditure (excluding financial transactions, Table 5.3, item 4.a2) fell sharply, by almost €12 billion. This was partly due to central government shifting expenditure to the new debt-financed Infrastructure and Climate Neutrality Fund.**{#par-e7i689}
****Core budget relative to the budget plan****{#par-o52i18}
****With the increase described above, the deficit remained €16 billion less than budgeted. Lower expenditure contributed somewhat more strongly to this than additional revenue.** Of the latter, €3½ billion was attributable to taxes (including the global revenue shortfall budgeted as a precautionary item). Moreover, the budget plan had not factored in return flows of crisis assistance transfers from emergency borrowing (actual figure: €1½ billion) or programme-related revenue from the budget (actual figure: €1 billion). On the expenditure side, investment, in particular, remained below budget. This lower investment spending of €7½ billion was spread across several items. A notable portion of this can be assigned to the item for residual spending authorisations for construction measures from previous years, according to figures added up in accordance with the budget classification table scheme. An item for residual authorisations was earmarked as investment expenditure for the first time in 2025, helping to meet the new minimum investment ratio in the plan.**{#par-oaa72i}
{#par-o422i9}{#par-o8ui41}{#par-oa1351}{#par-oa3i1a}{#par-o7e947}{#par-uaoo6o}{#par-i23a5a}{#par-iui295}{#par-e3e642}{#par-i8i289}{#par-ue1a32}{#par-a84o66}{#par-ie682a}{#par-ea87a7}{#par-a3u91u}{#par-eu1436}{#par-a528o7}{#par-e5565a}{#par-ea5838}{#par-e9i1a9}{#par-i3ea31}{#par-a3eu27}{#par-u91915}{#par-ooai44}{#par-eiu11o}{#par-iu2923}{#par-ei1587}{#par-ii657o}{#par-ee928i}{#par-io1766}{#par-ae1772}{#par-e8u94o}{#par-eue555}{#par-u67i47}{#par-ii9a37}{#par-a8u921}{#par-a925a2}{#par-e16284}{#par-oeooi2}{#par-eaei3i}{#par-o9o429}{#par-e49oo4}{#par-e36218}{#par-ia859a}{#par-uo3uu9}{#par-a9ai8a}{#par-o2a949}{#par-i14996}{#par-a754ue}{#par-a26u42}{#par-au1985}{#par-i1io11}{#par-uoea5i}{#par-e47235}
| **Table 5.3: Key central government budget data**{#par-uiau16} € billion (unless otherwise indicated) ||||||
|------------|---------------------------------------------------------------------------------------------------|-----------------|-----------------|------------------------------------|-----------------|
| **Item** | | **Actual 2024** | **Target 2025** | **Actual 2025** **(January 2026)** | **Target 2026** |
| **1.** | **Fiscal balances (surplus: +, deficit: -)** | | | | |
| **1.a** | **Core budget** | − 25.0 | − 81.9 | − 65.4 | − 98.1 |
| **1.b** | **Off-budget entities with borrowing plan figures¹** | − 43.2 | − 64.4 | − 36.2 | − 90.7 |
| | **of which:** | | | | |
| **1.b1** | **Infrastructure and Climate Neutrality Fund** | - | − 37.2 | − 24.0 | − 58.1 |
| **1.b2** | **Armed Forces Fund** | − 17.2 | − 24.1 | − 19.5 | − 25.5 |
| **1.b3** | **Climate and Transformation Fund** | − 23.1 | − 3.9 | 4.9 | − 2.1 |
| **1.b4** | **Other^2^** | − 3.0 | 0.8 | 2.4 | − 5.1 |
| **1.c** | **Off-budget entities without borrowing plan figures^1,3^** | 19.5 | - | 17.8 | - |
| **1.d** | **Central government total (1.a + 1.b + 1.c)** | − 48.7 | − 146.3 | − 83.8 | − 188.8 |
| **1.e** | **Central government total excluding financial transactions** | − 63.0 | − 129.9 | − 82.0 | − 179.2 |
| **2.** | **Data relevant to the debt brake (core budget)** | | | | |
| **2.a** | **Transfer to (-)/withdrawal from reserves (+)** | - | - | - | - |
| **2.a-n** | **Memo item: Level of general reserves** | 10.7 | 10.7 | 10.7 | 10.7 |
| **2.b** | **Coin seigniorage** | 0.2 | 0.1 | 0.1 | 0.1 |
| **2.c** | **Net borrowing (-)/repayment (+) (1.a + 2.a + 2.b)^4^** | − 24.8 | − 81.8 | − 65.2 | − 98.0 |
| **2.d** | **Cyclical component in the budget procedure^5^** | − 22.9 | − 18.2 | − 7.4 | − 15.6 |
| **2.d-n** | **Memo item: Bundesbank cyclical component** | − 1.4 | − 5.9 | − 5.9 | − 5.1 |
| **2.e** | **Balance of financial transactions** | − 1.4 | − 16.4 | − 15.4 | − 9.6 |
| **2.f** | **Structural net borrowing (-)/repayment (+) (2.c. − 2.d. − 2.e)** | − 0.5 | − 47.1 | − 42.5 | − 72.7 |
| | **darunter:** | | | | |
| **2.f1** | **Sectoral exemption for defence spending** | - | − 32.0 | − 28.6 | − 57.6 |
| **2.f1-n** | **Memo item: Increase in defence spending vis-à-vis Actual 2024^6^ (e)** | - | 14 | 11 | 38 |
| **2.g** | **Structural net borrowing (-)/repayment (+) excluding sectoral exemption (2.f − 2.f1)** | − 0.5 | − 15.2 | − 13.9 | − 15.2 |
| **2.h** | **Standard limit of 0.35 % of** **^7^** | − 5.9 | − 15.2 | − 13.5 | − 15.2 |
| **2.h-n** | **Memo item: Overshoot (+)/undershoot (-)** | − 5.4 | 0.0 | 0.4 | - |
| **2.i** | **Balance on control account^8^** | 58.0 | 58.0 | 57.6 | 57.6 |
| **2.j** | **Total outstanding repayment amount (repayment plan requirement)** | | | | |
| **2.j1** | **Emergency borrowing (2020 to 2023)⁹** | 326.4 | 326.4 | 324.7 | 324.7 |
| **2.j2** | **Armed Forces Fund and Infrastructure and Climate Neutrality Fund borrowing** | 23.0 | 84.3 | 66.5 | 150.0 |
| **2.j-n** | **Memo item: Total outstanding repayment amount from** **grants (e)^10^** | 65 | 92 | 92 | 118 |
| **3.** | **Net borrowing of off-budget entities (outside the debt brake)** | | | | |
| **3.a** | **Net borrowing of Armed Forces Fund** | − 17.2 | − 24.1 | − 19.5 | − 25.5 |
| **3.b** | **Borrowing authorisation remaining thereafter** | 77.0 | 52.9 | 57.5 | 32.1 |
| **3.c** | **Net borrowing of Infrastructure and Climate Neutrality Fund** | - | − 37.2 | − 24.0 | − 58.1 |
| **3.c-n** | **Memo item: Increase in infrastructure investment vis-à-vis Actual 2024^11^** | - | 4.7 | − 1.0 | 15.8 |
| **3.d** | **Borrowing authorisation remaining thereafter** | - | 462.8 | 476.0 | 417.9 |
| **4.** | **Additional core budget figures** | | | | |
| **4.a** | **Expenditure^12^** | 465.7 | 502.5 | 493.3 | 524.5 |
| | **of which:** | | | | |
| **4.a1** | **Investment** | 56.7 | 62.7 | 55.4 | 58.4 |
| **4.a2** | **Investment excluding financial transactions** | 50.8 | 45.4 | 39.2 | 47.9 |
| **4.a3** | **Investment in central government infrastructure^11^** | 30.9 | 20.9 | 18.1 | 24.2 |
| **4.a4** | **Investment ratio (relevant for Infrastructure and Climate Neutrality Fund)** | 11.6 % | 10.0 % | 8.7 %^16)^ | 10.5 % |
| **4.a4-n** | **Memo item: of which financed via sectoral exemption for defence spending (2.f1) (Actual: e)¹³** | - | 2.4 | 1 1/2 | 3.9 |
| **4.a5** | **Interest** | 34.2 | 30.2 | 29.9 | 30.2 |
| **4.a6** | **Grants to the statutory pension insurance scheme** | 107.5 | 114.1 | 114.1 | 119.0 |
| **4.a7** | **Global spending increases/cuts** | - | − 6.0 | - | − 8.8 |
| **4.b** | **Revenue^12,14^** | 440.6 | 420.6 | 427.9 | 426.4 |
| | **of which:** | | | | |
| **4.b1** | **Tax revenue^15^** | 375.0 | 386.8 | 388.6 | 387.2 |
| **4.b2** | **From** | 13.5 | 0.0 | 0.0 | 10.6 |
{#par-a2a434}
****Core budget with regard to the debt brake****{#par-uo4132}
****In the provisional settlement calculating the difference between the upper limit on borrowing (as determined under the debt brake rules) and the actual amount borrowed,** [\[11\]](#_ftn_root_11)**central government slightly exceeded the borrowing limit under the debt brake** (by just under €½ billion; see Table 5.3, item 2.h-n). It thus failed to fulfil its objective of adhering exactly to the limit, despite the smaller than planned deficit. This is because nominal growth was considerably higher than in the budget plan, reducing cyclically permissible borrowing by €10 billion. However, tax revenue was only €3½ billion higher than planned (including deduction of the budgeted global revenue shortfall), and the further debt brake-related relief compared with the plan was also unable to fully offset the lower borrowing limit. The amount by which the limit was exceeded is offset against the balance on the control account. However, this balance still stands at almost €58 billion thereafter.**{#par-iuau53}
****The investment ratio in the core budget stood at 10 % in the budget plan, but ultimately worked out at just 8.7 %** (Table 5.3, item 4.a4). To actually hit the minimum ratio, central government's core budget would have needed to see an additional €6 billion in investment. The new Infrastructure and Climate Neutrality Fund was nevertheless able to borrow to finance its projects (including for investments shifted from the central government budget) because the requisite minimum investment ratio of 10 % only needs to be achieved in the budget plan.[\[12\]](#_ftn_root_12)**{#par-a31ui4}
****All in all, it seems advisable to incorporate the actual investment ratio into the settlement.** [\[13\]](#_ftn_root_13)This would provide better safeguards for additional investment. So far, investment has often come to less than the amounts budgeted for in the core budget. If the option to borrow is determined solely by what is in the budget plan, funds in the budget that are actually earmarked for investment are left available for other purposes.**{#par-a991io}
****Central government borrowing for infrastructure purposes within the Infrastructure and Climate Neutrality Fund came to €14 billion. Defined as per the Bundesbank's recommended definition, central government's infrastructure investment in the core budget and the Infrastructure and Climate Neutrality Fund combined was slightly down on 2024.** The Bundesbank uses a narrower definition of infrastructure investment. In comparison with the way central government counts investment expenditure in the budget, the Bundesbank definition disregards, in particular, items with no relation to government infrastructure (see Table 5.3, item 4.a3 for the expenditure included in the core budget).[\[14\]](#_ftn_root_14)**{#par-u35297}
{#par-i85u7o}
**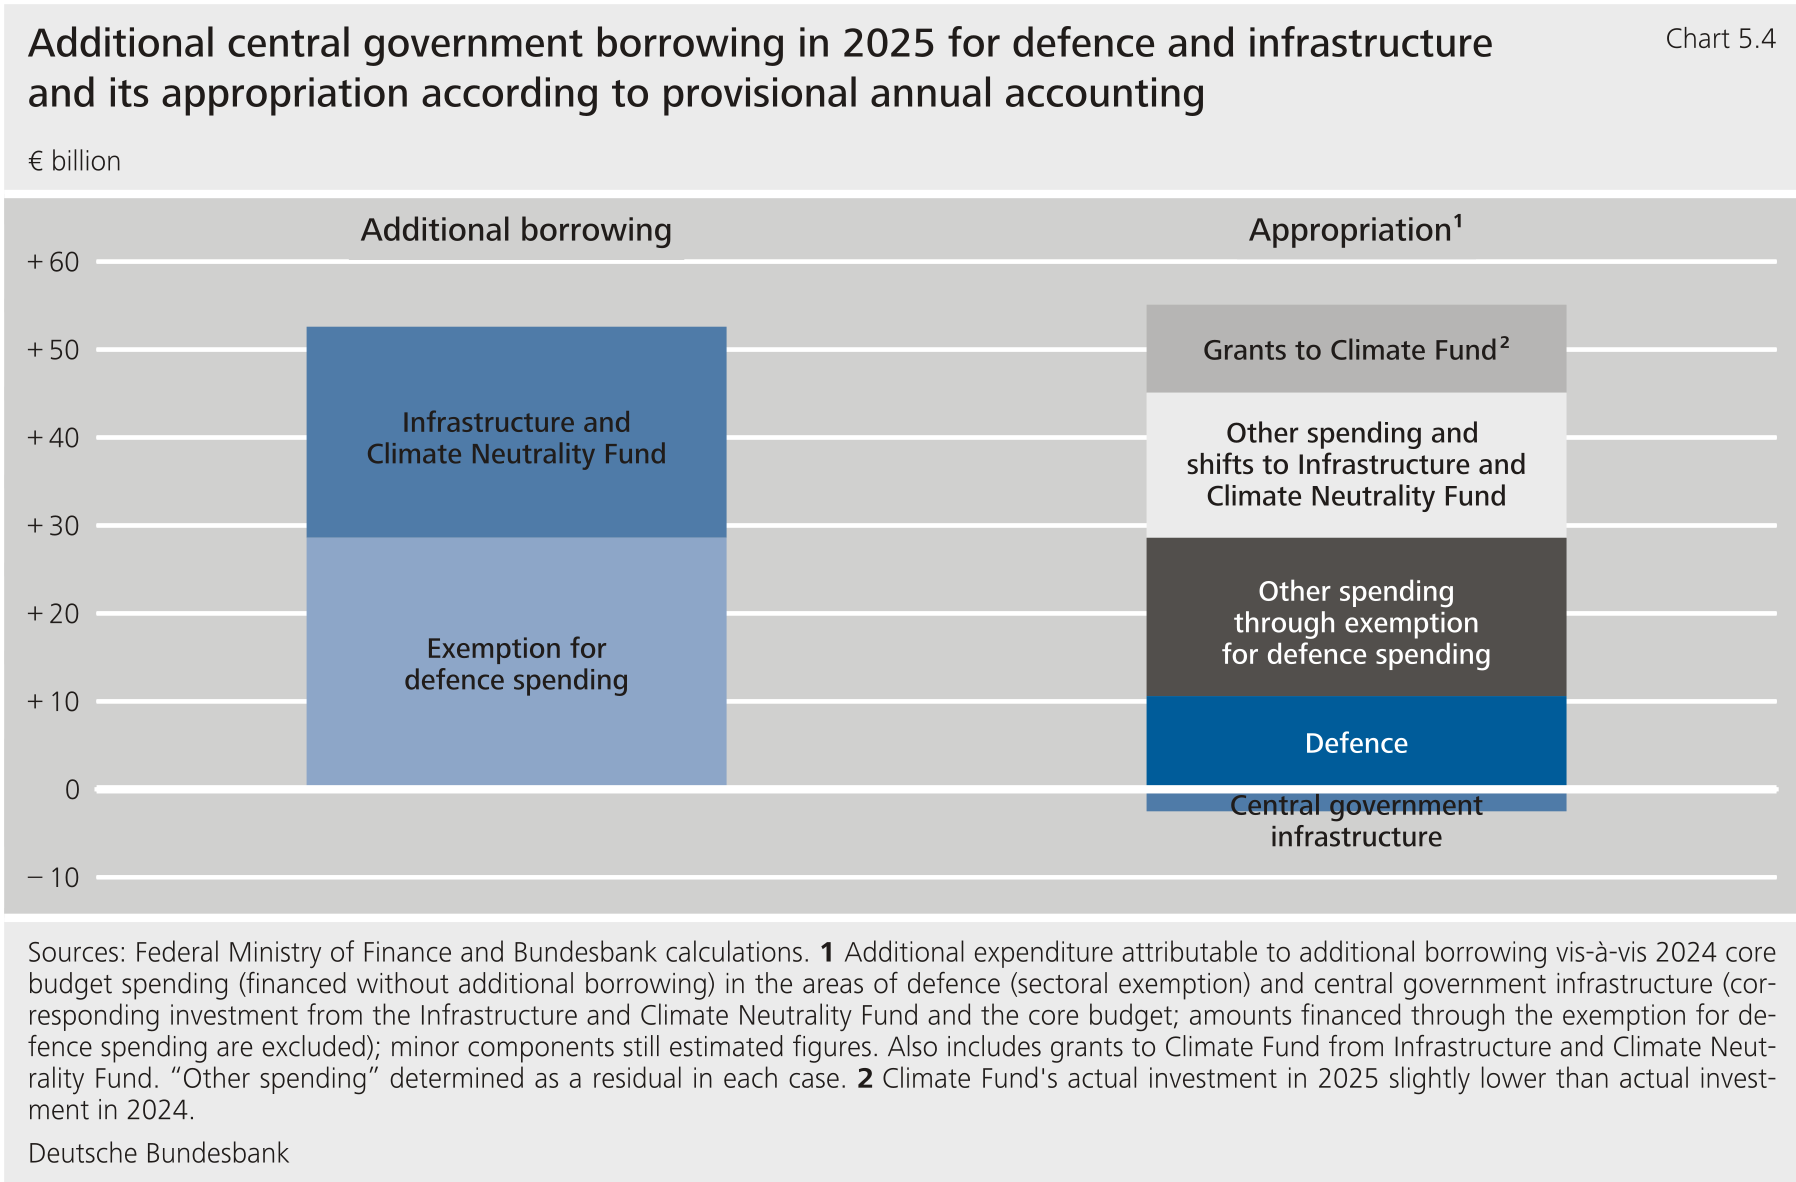**
****The exemption for defence spending allowed for borrowing of almost €29 billion (Table 5.3, item 2.f1).** **expenditure from the core budget is likely to have risen significantly, but borrowing under the sectoral exemption was significantly higher.** The sectoral exemption excludes defence spending above 1 % of from the debt brake. The aim is to rapidly strengthen Germany's defence capabilities within . The Federal Ministry of Finance has not yet reported on the relevant developments in spending in this regard. However, it has reported that defence spending has gone up by just over €9 billion[\[15\]](#_ftn_root_15) and Ukraine aid has been increased by €½ billion compared with 2024. These items closely align with the reach of the sectoral exemption. Other expenditure also falling under the sectoral exemption (total target: €5 billion) could have risen by just over €1 billion.**{#par-o33i19}
****Off-budget entities****{#par-ie3ae6}
{#par-o99ie4}
**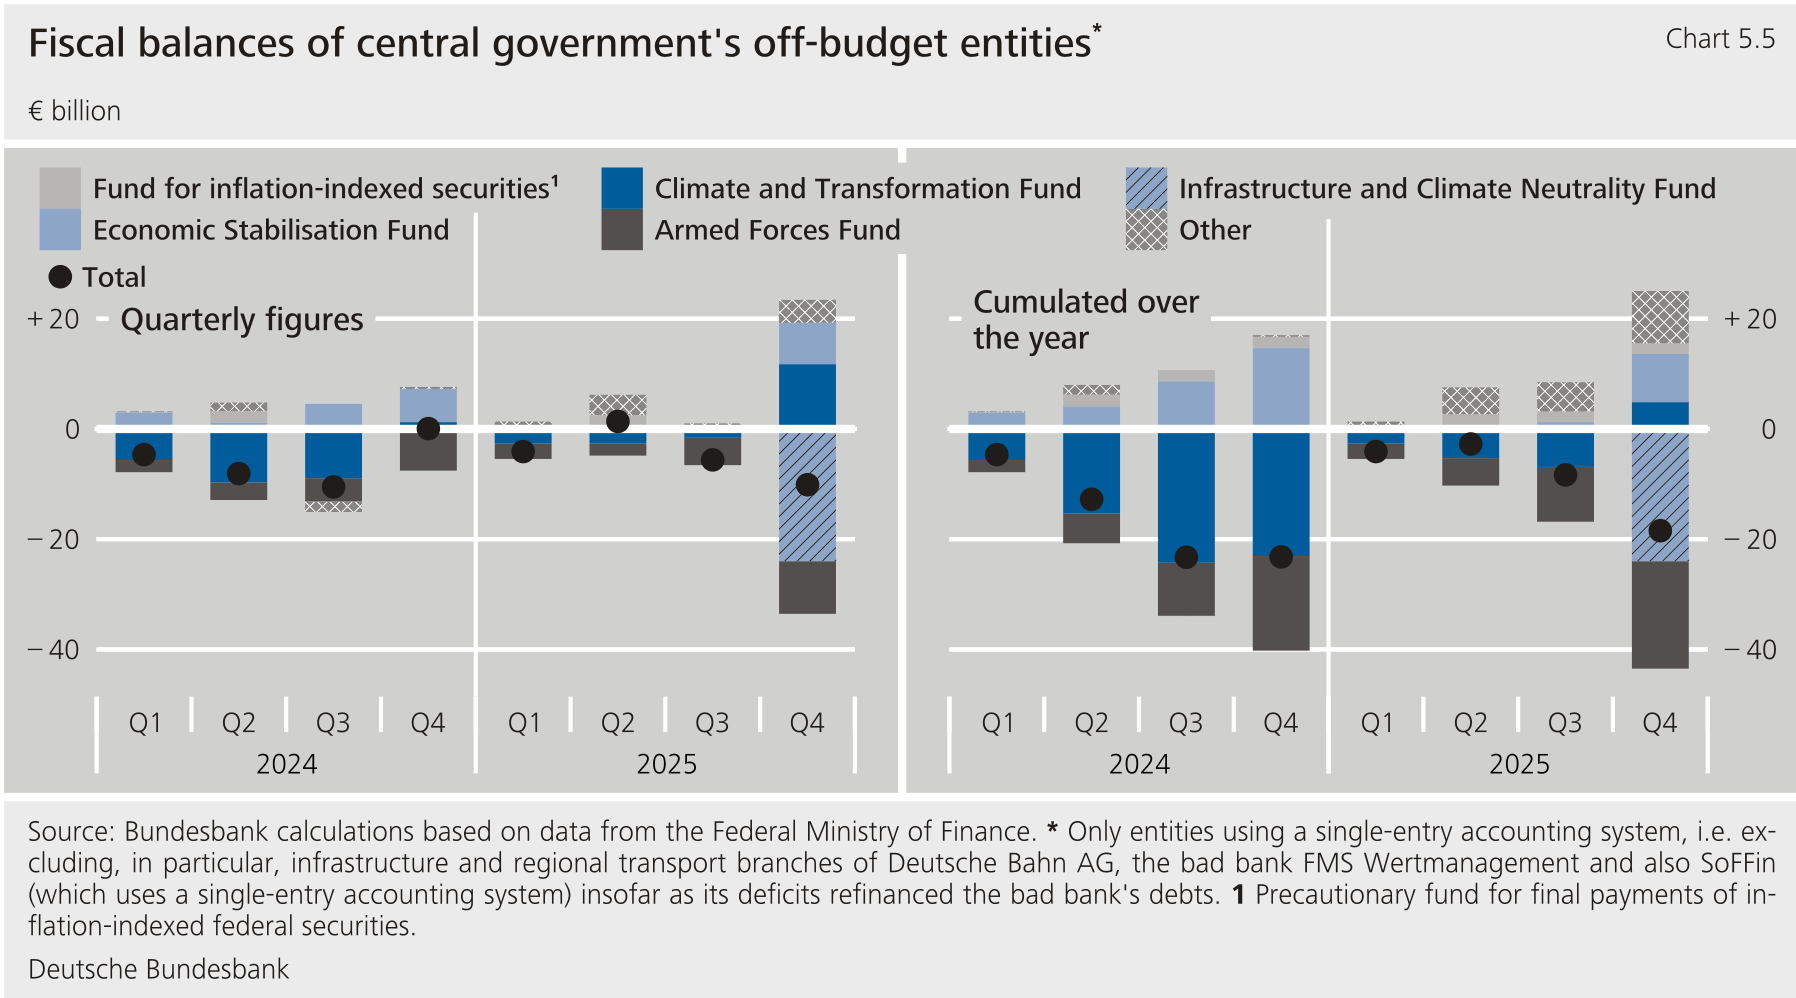**
****Central government's off-budget entities** [\[16\]](#_ftn_root_16)**recorded a deficit of just over €18 billion, which was slightly down on the previous year's figure. In some cases, central government ended up bulking up reserves in off-budget entities through borrowing. Some burdens were also shifted to or from the core budget:****{#par-ai3i92}
* ****The new Infrastructure and Climate Neutrality Fund posted a deficit of €24 billion.** Of this, €10 billion was attributable to a transfer to the Climate Fund and €1½ billion to hospitals' "immediate transformation costs". The remainder appears to have largely been channelled into central government infrastructure investment. Given the decline of almost €13 billion in such investments in the core budget (Table 5.3, item 4.a3), this constitutes, looking at the figures, expenditure outsourced by the core budget.
**The deficit was €13 billion lower than budgeted.** This was mainly because the €8½ billion in funds earmarked for the federal states was not disbursed. The funds are now available for the federal states to draw on over time.**
{#par-i45166}
* ****The Armed Forces Fund reported a deficit of just over €19 billion,****up by just over €2 billion on the year.** This was mostly down to higher spending on military procurement. Nevertheless, the result was still €4½ billion below budget.**
{#par-iue35e}
* ****The Economic Stabilisation Fund posted a surplus of almost €9 billion. This was €5 billion lower than in the previous year.** Repayments of assistance loans granted by central government to firms during the -19 pandemic and the energy price crisis came to less than before, reducing the surplus. Central government does not release borrowing plan figures for this fund.**
{#par-au42i5}
* ****By contrast,**,**the off-budget special fund formed during the financial market crisis, improved its result by €5½ billion and posted a surplus of the same amount.** This was mainly due to repayments of loans by the federal bad bank FMS Wertmanagement. It appears that FMS Wertmanagement markedly reduced its stock of impaired receivables. Again, central government does not provide borrowing plan figures for this particular fund.**
{#par-o88193}
* ****The Climate Fund's result saw significant improvement, jumping by €28 billion to reach a surplus of €5 billion. It thus closed €9 billion more favourably than planned.** Central government's core budget played the largest role in the improvement on 2024, as it took over responsibility for subsidies for environmentally friendly electricity (2024: just over €18 billion). The only fresh burden counterbalancing the new debt-financed grant of €10 billion from the Climate and Infrastructure Fund was the gas storage levy in the amount of €3 billion. Investment by the fund even declined slightly on the year. Besides that, revenue from sales of emission allowances grew by €3 billion. This was primarily due to the increased national carbon price per tonne, which rose from €45 in 2024 to €55. The main reason for the better than planned result was that central government had once again been cautious in its estimates for a number of expenditure items. The Climate Fund's reserve was budgeted at €2 billion for 2026, but now stands at €11 billion.**
{#par-a4e464}
* ****The deficit of €4 billion recorded by the Digitalisation Fund in 2024 has now been eliminated.** Central government dissolved this fund in 2024. This involved subsuming the reserves into the core budget with an effect on the balance. At the same time, the core budget took over the fund's tasks. Last year, it then passed some of those tasks on to the new Infrastructure and Climate Neutrality Fund (for example, furthering expansion of the broadband network).**
{#par-oee1u9}
* ****The 2021 Flood Assistance Fund improved its result by almost €1½ billion due to central government forming a reserve there.** As in previous years, it was envisaged that the core budget would offset the fund's expenditure by means of a grant. However, for the first time, the core budget transferred the fund's budgeted spending amount instead of matching the actual outflows, which regularly turn out to be much lower. Central government ultimately set aside just under €1½ billion as a debt-financed reserve. In future, central government will be able to ease the burden on its core budget by having the fund draw on the reserve to finance expenditure, doing away with the need for a grant. However, that will not be enough to close the structural budget gaps set to emerge in the medium term (see Chapter 3.2 "[Outlook for 2026 and beyond](#3.2-Outlook-for-2026-and-beyond)" below).**
{#par-e36u4a}
* ****Turning to the other off-budget special funds, the surpluses of entities receiving provisions for civil servant pensions rose slightly to a total of €5 billion. In view of the exemption for defence spending, it is now a case of ensuring that pension funds are utilised as originally intended going forward.** Pension funds are supposed to prevent the central government budget from needing to borrow more in net terms when pension benefits fall due. While the sectoral exemption has also removed the borrowing limit for the relevant pension expenditure, it would be inappropriate to use the old reserves as well as the new debt-financed ones for other purposes. In order to prevent such a scenario, it would be logical to make sure that recourse to borrowing under the sectoral exemption cannot be used as a first resort for financing future pension burdens.**
{#par-e3693e}
### **3.2 Outlook for 2026 and beyond** {#tar-10}
****Central government is planning a further sharp increase in deficits this year.** The deficit in the core budget is expected to increase by €33 billion compared with the 2025 result. Planned expenditure under the exemption for defence spending alone is up €29 billion on the 2025 outturn. An even bigger increase of €54 billion is envisaged in the case of the off-budget entities,[\[17\]](#_ftn_root_17) with the Infrastructure and Climate Neutrality Fund making up €34 billion of that. The Climate Fund contributes €7 billion to the overall increase, as it is set to generate a deficit again (€2 billion). The deficit in the Armed Forces Fund is expected to increase by a further €6 billion. The precautionary fund for inflation-indexed federal securities is now looking at a deficit of €5 billion. This is due to an upcoming payment that will compensate for the cumulative inflation over the lifetime of an inflation-indexed federal debt instrument upon redemption. The fund will be making this payment out of its reserves. The core budget's recouping of transfers made in previous years for own securities holdings will also be a factor.**{#par-o35u48}
****Looking ahead to 2027, developments in the intervening months have significantly reduced the need for action. From 2028 onwards, however, the need for action will still be large.** The tax estimate from autumn 2025 occasioned a significant upward revision of around €7 billion per year compared with the estimates in summer 2025's fiscal plan. This also made it possible to maintain the core budget reserve of €11 billion beyond 2026. These two factors alone could virtually halve the €34 billion need for action expected for 2027. In addition, central government could deploy the higher than planned reserves in the Climate Fund and the Flood Assistance Fund to ease the burden on its core budget. By contrast, looking ahead to 2028 and 2029, the needs for action remain very large -- in the order of over €50 billion and €60 billion, respectively.**{#par-oaa78i}
****Owing to these needs for action, it makes sense for central government to avoid adding to the burdens on its budget and to subject its existing expenditure and tax concessions to a rigorous review.**With the social security funds beset by demographic pressures, the Federal Government has set up expert commissions tasked with finding ways to alleviate the funds' spending pressures -- and thereby ease the burden on central government finances. However, the benchmark figures for the 2027 draft budget and for the fiscal planning up to 2030, which are both due in the spring, cannot yet factor in any results from the commissions' work.**{#par-e6a54i}
****So as to better ensure that investment in infrastructure increases, it is important that the scope for borrowing afforded by the Infrastructure and Climate Neutrality Fund be used in a more targeted way. The best way to safeguard sound central government finances is through further reform of the debt brake.** The Bundesbank has made concrete proposals regarding those points in recent months (see footnote 3). Those recommendations aim to make sure that, with debt service set to increase significantly going forward, Germany does actually see, as far as possible, a corresponding improvement in defence capabilities and infrastructure in return. They are also designed to reliably safeguard sound government finances, take the rules into account, and facilitate a relatively steady fiscal policy.**{#par-ee5iu4}
**4 State government budgets [\[18\]](#_ftn_root_18)** {#tar-11}
----------------------------------------------------------------
### **4.1 Results for 2025** {#tar-12}
****State government core budgets posted a deficit of €7½ billion in 2025. This was on a par with the year before, though positive one-off effects did provide relief.**Revenue rose by 4 % (just short of €20 billion). At 5 %, taxes rose somewhat more sharply, with one-off effects having a favourable effect: the payout period for tax-free and social contribution-exempt inflation compensation bonuses expired at the end of 2024, a one-off effect boosted revenue from inheritance tax, and withholding tax on interest income and capital gains saw particularly brisk growth. Resources from central government's new Infrastructure and Climate Neutrality Fund were not yet disbursed to federal states in 2025. Total expenditure climbed by 4 % (+ €20 billion), primarily driven by personnel expenditure (+ €9 billion) -- a major expenditure item -- and payments to administrations (+ €8 billion). The latter mainly comprise transfers to local governments, which increased by €6 billion. A significant drop in acquisitions of participating interests (− €3½ billion compared with the previous year's high figure) exerted a deficit-reducing one-off effect. Fixed asset formation in the core budgets fell slightly. It should be borne in mind that around half of fixed asset formation takes place via the state governments' off-budget entities (including universities) and their share recently rose. Fourth quarter results for the off-budget entities are not yet available.**{#par-e942u2}
{#par-e9i6a4}
**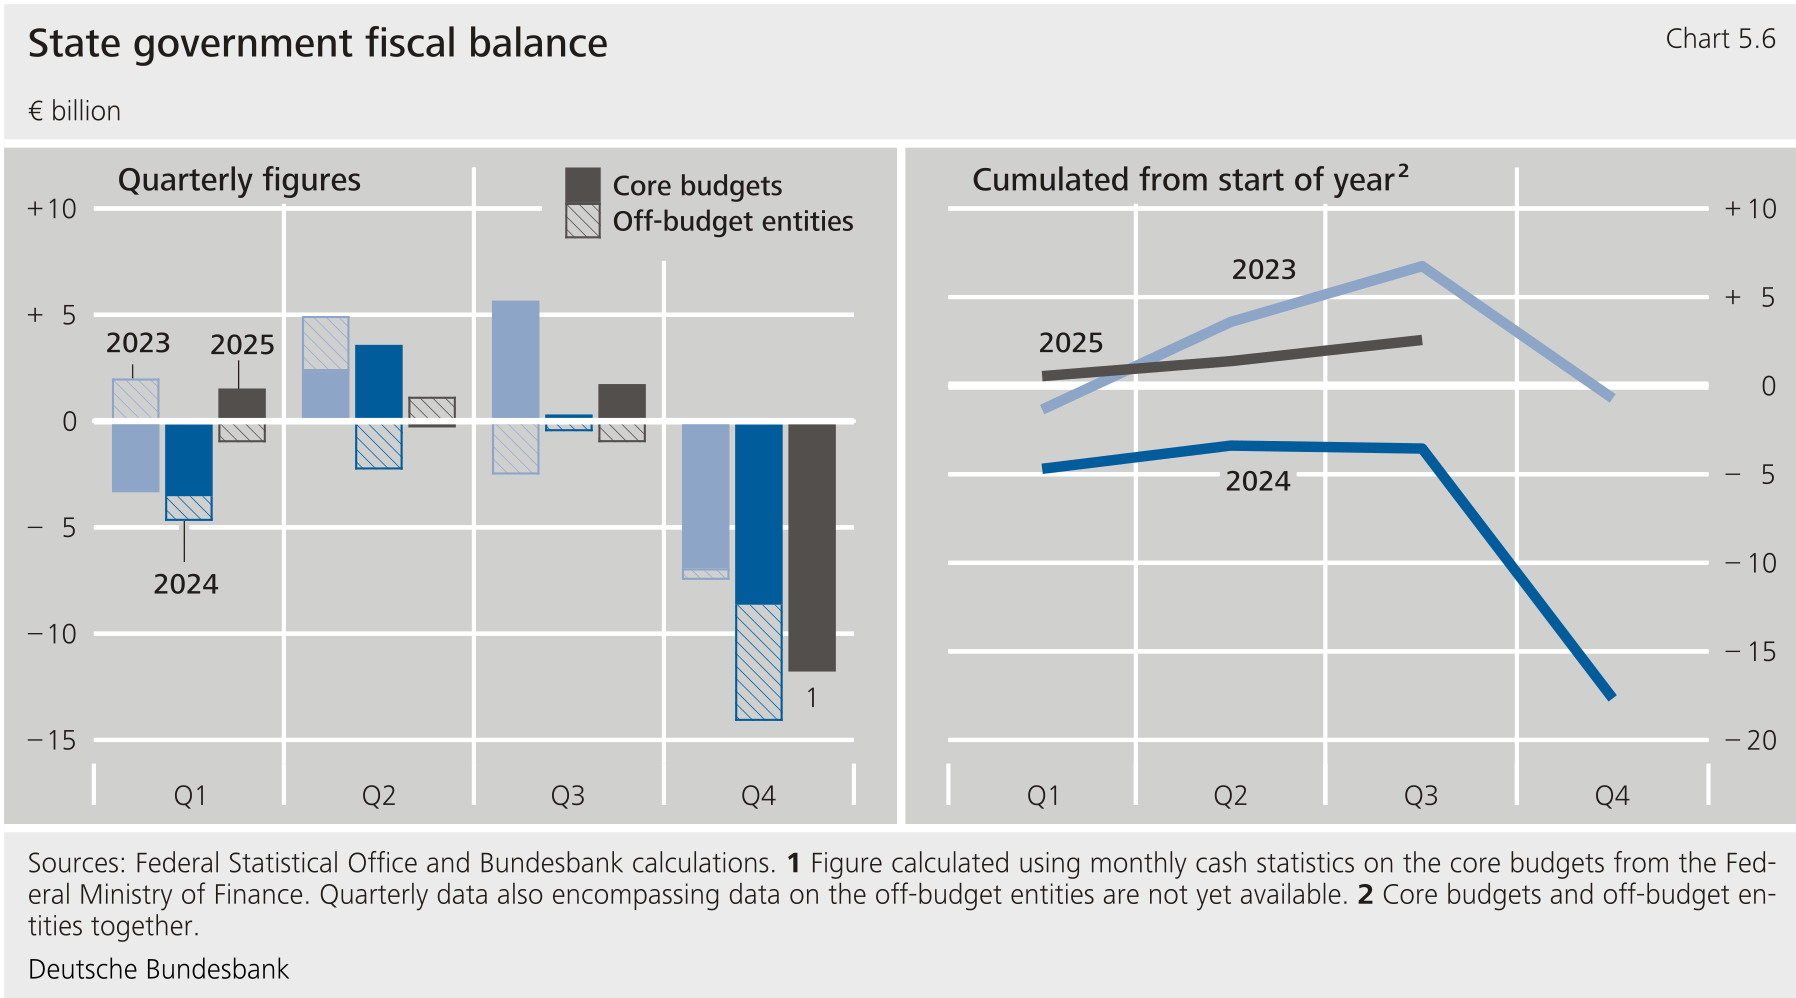**
****Including off-budget entities, the state government deficit may have fallen somewhat in 2025.**Following the three quarters for which data are available so far, off-budget entities had improved their result by €3 billion compared with the previous year.**{#par-e52e4a}
****Only seven federal states made use of the structural borrowing scope of up to 0.35 % of** **available to them since 2025 (€15 billion for all federal states combined).** [\[19\]](#_ftn_root_19)In doing so, the seven federal states planned structural borrowing of just under €5 billion in total. Saarland and Saxony-Anhalt still declared a state of emergency in 2025. Saarland planned to use emergency borrowing to finance the projects of its transformation fund, while Saxony-Anhalt intended to address the ongoing fallout from the -19 pandemic and strengthen pandemic resilience. Meanwhile, the other federal states planned to balance their budgets without recourse to structural debt or emergency borrowing. Unlike for central government, however, settlement figures are not yet available for state government. It is thus still unclear to what extent federal states excused deficits as cyclical, excluded balances from financial transactions or drew on reserves.[\[20\]](#_ftn_root_20)**{#par-eaeo3i}
### **4.2 Outlook for 2026 remains uncertain** {#tar-13}
****Based on the plans as they currently stand, eleven federal states will use the new structural borrowing option in 2026.** [\[21\]](#_ftn_root_21) If these federal states access all of the available funds, state government structural borrowing will increase to just under €9 billion. In view of the infrastructure backlog as well as the fact that some states already have high debt burdens and that state governments are responsible for the financial resources of their local governments, it is crucial to ensure that the new scope for deficits is used with caution.**{#par-u27649}
****The state government deficit for 2026 is difficult to predict. This is partly due to the Infrastructure and Climate Neutrality Fund, via which the federal states receive funds from central government and can thus relieve their budgets.** The extent to which the federal states actually use the new structural borrowing scope is not the only relevant factor for the state government deficit.[\[22\]](#_ftn_root_22) As in 2025, state governments will probably excuse additional deficits to some degree as cyclical, acquire financial assets beyond the debt brake borrowing and draw on reserves. The deficits would thus be significantly higher than structural net borrowing under the debt brakes. By contrast, if the federal states draw on resources from the Infrastructure and Climate Neutrality Fund, this will have a negative impact on central government's budget balance. State governments have the option of using these resources to expand their investment and investment grants to their local governments. However, they could also use the funds for projects that they would otherwise have financed themselves, thereby reducing their deficits.**{#par-u1o774}
**5 Social security funds** {#tar-14}
-------------------------------------
### **5.1 Pension insurance scheme** {#tar-15}
#### **5.1.1 2025 as a whole**
****The finances of the statutory pension insurance scheme deteriorated perceptibly in 2025.** Its deficit amounted to almost €4 billion and probably increased by around €2 billion compared with 2024.[\[23\]](#_ftn_root_23) The sustainability reserve fell to just over €41 billion at the end of 2025 (just under 1.4 times the scheme's monthly expenditure). Nevertheless, its funds still exceeded the statutory minimum of 0.2 times the scheme's monthly expenditure by a significant €35 billion.**{#par-oe35oi}
{#par-i59a84}
**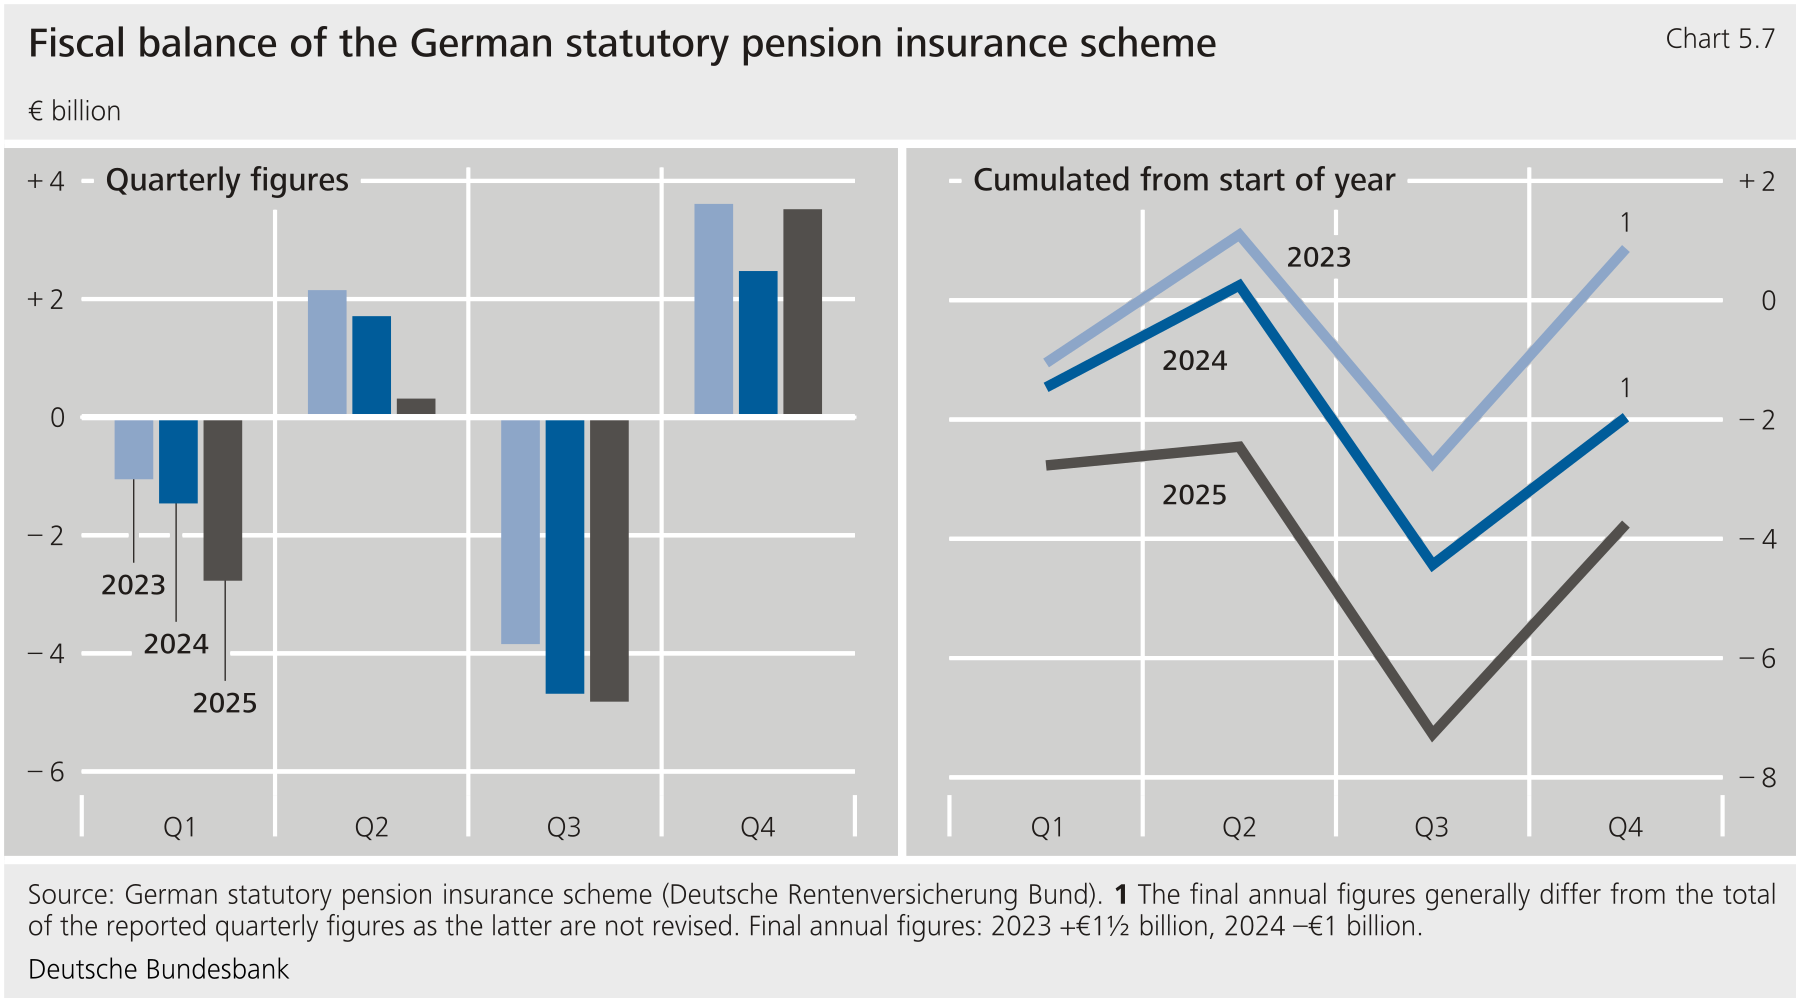**
****At 5½ %, growth in expenditure was much stronger than that in revenue. On an annual average, pensions rose by 4 % per capita.** The number of pensions grew by ½ %. The pension insurance scheme also paid out even higher flat-rate supplements for persons drawing reduced earning capacity pensions. In addition, expenditure on pension recipients' health insurance rose significantly as a result of the sharp increase in the supplementary contribution rates set by the statutory health insurance institutions.[\[24\]](#_ftn_root_24) Total revenue went up by almost 5 %. Alongside significant wage increases, this was due to the fact that earnings subject to compulsory contributions were replacing tax-free and social contribution-exempt inflation compensation bonuses from the previous year.**{#par-oi3e16}
#### **5.1.2 Outlook from 2026 to 2028**
****The financial situation is likely to deteriorate further in 2026 and 2027. According to the pension insurance report,** [\[25\]](#_ftn_root_25)**the deficit will expand to €9½ billion in 2026 and will probably rise to more than €18 billion in 2027.**As per the report, revenue, like earnings subject to compulsory contributions, will increase by 3½ % and 3 %, respectively. Expenditure growth will be significantly stronger, at 4½ % and almost 5½ %, respectively. The gap between growth in expenditure and that in revenue will thus widen every year. As a result, the financing gap will increase and the sustainability reserve will shrink rapidly.**{#par-o2i4ie}
****In 2028, a sharp increase in the contribution rate is likely to be necessary in order to maintain the minimum reserve level.** According to the pension insurance report, the contribution rate will then rise from its current level of 18.6 % to 19.8 %.**{#par-ouo3uu}
#### **5.1.3 Longer-term developments and the Pension Commission**
****Pension finances will increasingly be burdened by demographic shifts as particularly large birth cohorts gradually enter retirement. The number of pensions in payment will thus rise steeply.** This will put pressure on both the expenditure and revenue sides. Under current legislation, the contribution rate will then have to be raised further, possibly reaching just over 21 % by the end of the 2030s. The replacement rate is the key metric for expenditure developments. This will remain unchanged at 48 % until 2031 based on the recently adopted pension package.[\[26\]](#_ftn_root_26) Under current legislation, it will then fall gradually. According to the pension insurance report, it will be around 45 % at the end of the next decade. A rising contribution rate and a falling replacement rate are also likely in the years that follow based on current legislation.[\[27\]](#_ftn_root_27)**{#par-a542e2}
****The Federal Government is planning a comprehensive pension reform. The Pension Commission has been tasked with submitting proposals on this by the middle of this year**. The Federal Government set up the Pension Commission at the end of last year, shortly after the adoption of its latest pension package. Its members comprise academic experts and political representatives.**{#par-iu1u2o}
****In order to alleviate the pressures on pension finances and the central government budget, it would make sense to reduce the financial incentives for early retirement and to link the retirement age to life expectancy after 2030.** This would boost employment and strengthen the contribution base. Full pensions, i.e. pensions without any benefit reductions, after 45 years of contributions create incentives for early retirement: while paying the same contributions overall, beneficiaries receive higher pension entitlements than insurees of the same age with fewer years of insurance. This goes against the equivalence principle, which ensures that pension entitlements are linked to contributions paid. Moreover, longer life expectancy and unchanged statutory retirement ages also mean a lower ratio of years of employment to years of retirement.[\[28\]](#_ftn_root_28) In order to counteract this, after 2030, the minimum age for the earliest possible entry into retirement and the statutory retirement age could be linked to life expectancy, which will probably continue to rise. These measures would not only strengthen the revenue base of the pension insurance scheme, they would also limit expenditure growth. As a result, the rise in the contribution rate would be less sharp, which would also ease the burden on the central government budget. Furthermore, longer working lives support potential growth and the general government revenue base.**{#par-ui239a}
### **5.2 Federal Employment Agency** {#tar-16}
****The Federal Employment Agency posted a deficit of just over €4 billion in 2025.** [\[29\]](#_ftn_root_29) Insolvency benefit and winter employment compensation, which are funded via specific contributions, generated a surplus of €½ billion.[\[30\]](#_ftn_root_30) The core budget, which is financed by contributions, posted a deficit of €4½ billion. Once the free reserves of just over €3 billion had been used up, a gap of €1½ billion remained. Central government closed this gap with a multi-year loan.[\[31\]](#_ftn_root_31)**{#par-a5326o}
{#par-ae7i46}
**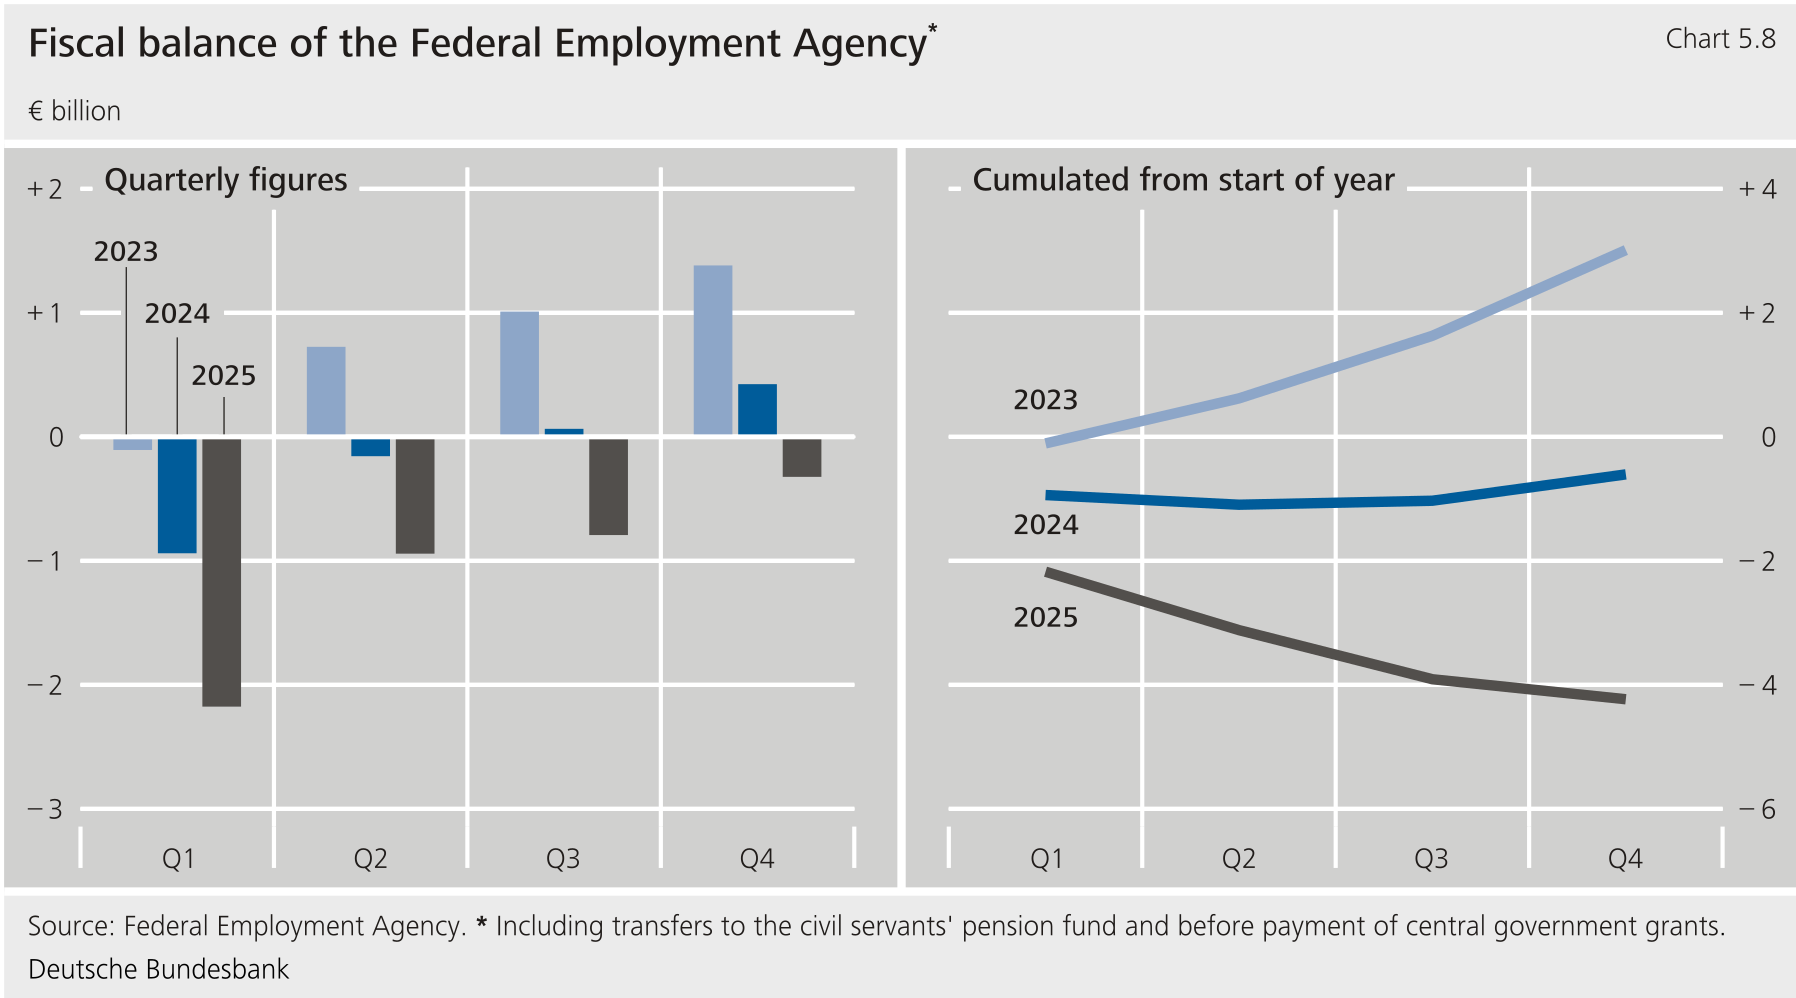**
****Compared with the previous year, the Federal Employment Agency's outturn deteriorated significantly (2024: deficit of €½ billion), mainly because unemployment benefits -- a major expenditure item -- increased sharply.**Revenue growth was strong, at 7 %, which was partly due to the rise in the contribution rate for insolvency benefit payments. However, expenditure growth was more than twice as high (+ 15 %). At 19 %, unemployment benefits saw an even steeper rise, particularly because of the growing number of recipients (+ 11 %). Active labour market policy expenditure also increased sharply (+ 15 %). While the number of persons involved in measures tended to stagnate, central government transferred non-insurance-related tasks from the basic welfare allowance scheme in its budget to the Federal Employment Agency's budget (just under €1 billion).**{#par-o75663}
****The Federal Employment Agency expects its finances to improve only a little this year, anticipating a deficit of €3½ billion in its core budget.** A deficit of €4 billion is projected for the contribution budget, which central government will then fully offset with loans. Otherwise, it would have been necessary to increase the contribution rate to the Federal Employment Agency.It is thus presumed that central government loans totalling €5½ billion will be recorded at the end of 2026. The Federal Employment Agency is expected to repay these funds from surpluses once the economic situation improves. Its planned revenue is 3 % higher than the figure for 2025. Growth in contribution receipts is expected to be markedly weaker than in the previous year. Expenditure on unemployment benefits is expected to increase by only 1 % compared with the previous year's figure. While per capita payments will rise, the Federal Government expects that the labour market will recover to some extent and that the number of benefit recipients will thus fall somewhat. Looking at active labour market policy measures, the Federal Employment Agency projects strong growth.**{#par-io83e4}
****The Federal Employment Agency's planned outturn appears plausible: according to the Bundesbank's December 2025 Forecast for Germany,** [\[32\]](#_ftn_root_32)**the labour market is developing less favourably than assumed in the Federal Employment Agency's budget****.** This will put pressure on the Federal Employment Agency's finances that is not accounted for in its plans. However, it often tends to have quite generous expenditure appropriations for active labour market policy. It should therefore nevertheless achieve its planned outturn.**{#par-oe787u}
***This article is based on data available up to 17 February 2026, 11:00.***{#par-uiu32i}
**List of references** {#tar-17}
--------------------------------
**Deutsche Bundesbank (2026), [Government investment: gear new scope for borrowing towards infrastructure](https://publikationen.bundesbank.de/content/972822), Monthly Report, January 2026.**{#par-u35ia2}
**Deutsche Bundesbank (2025a), [Commentaries: Economic conditions and Public finances](https://publikationen.bundesbank.de/content/954658), Monthly Report, April 2025.**{#par-ea42ua}
**Deutsche Bundesbank (2025b), [Overview](https://publikationen.bundesbank.de/content/970806), Monthly Report, November 2025.**{#par-o27152}
**Deutsche Bundesbank (2025c), [Public finances](https://publikationen.bundesbank.de/content/957534), Monthly Report, May 2025.**{#par-i98i5u}
**Deutsche Bundesbank (2025d), [How the debt brake could be developed further](https://publikationen.bundesbank.de/content/972500), Reports and studies, November 2025.**{#par-i91eiu}
**Deutsche Bundesbank (2025e), [State government finances in 2024: situation worsens, large deficit for local governments](https://publikationen.bundesbank.de/content/968314), Monthly Report, October 2025.**{#par-e7e2ua}
**Deutsche Bundesbank (2025f), [Early, standard, late: when insurees retire and how pension benefit reductions and increases could be determined](https://publikationen.bundesbank.de/content/958722), Monthly Report, June 2025.**{#par-i63o7a}
**Deutsche Bundesbank (2025g), [Forecast for Germany: Economy gradually returns to recovery path](https://publikationen.bundesbank.de/content/973884), Monthly Report, December 2025.**{#par-u9a851}
**Deutsche Bundesbank (2023), [Public finances](https://www.bundesbank.de/content/817430), Monthly Report, November 2023.**{#par-a173oe}
**Deutsche Bundesbank (2016), [Monthly Report - February 2016](https://www.bundesbank.de/content/667048), Monthly Report, February 2016, pp. 68‑69.**{#par-o68176}
**Deutsche Bundesbank (2006), [A disaggregated framework for analysing public finances: Germany's fiscal track record between 2000 and 2005](https://www.bundesbank.de/content/706572), Monthly Report, March 2006, pp. 61‑76.**{#par-o6o52e}
**Federal Ministry of Finance (2026), [Vorläufiger Abschluss von Bundeshaushalt, und 2025](https://www.bundesfinanzministerium.de/Monatsberichte/Ausgabe/2026/01/monatsbericht-01-2026.html), Monatsbericht, January 2026, pp. 10‑30.**{#par-ia6932}
**Federal Ministry of Finance (2025a), [Haushaltsrechnung des Bundes 2024](https://www.bundeshaushalt.de/static/daten/2024/ist/Haushaltsrechnung_2024_Band_1_webg.pdf), Vol. 1, May 2025.**{#par-uo6i92}
**Federal Ministry of Finance (2025b), [Stabilitätsrat schafft Transparenz über Nutzung neuer Verschuldungsmöglichkeiten durch Bund und Länder](https://www.bundesfinanzministerium.de/Content/DE/Pressemitteilungen/Finanzpolitik/2025/12/2025-12-09-34-sitzung-des-stabilitaetsrats.html), press release, 34th meeting of the Stability Council on 9 December 2025.**{#par-u85au2}
**Federal Ministry of Labour and Social Affairs (2025), [Rentenversicherungsbericht 2025](https://www.bmas.de/SharedDocs/Downloads/DE/Rente/rentenversicherungsbericht-2025.pdf?__blob=publicationFile&v=2), November 2025.**{#par-a87iu4}
**Ministry of Finance for Hesse (2025), [Nachtragshaushalt 2025 und Soforthilfe für Kommunen beschlossen](https://hessen.de/presse/nachtragshaushalt-2025-und-soforthilfe-fuer-kommunen-beschlossen), press release of 13 November 2025.**{#par-o22169}
**Ministry of Finance for Lower Saxony (2025), [Nachtragshaushalt 2025 und Haushalt 2026 -- Sofortprogramm zur Stärkung von Investitionen und zur Entlastung der Kommunen](https://www.mf.niedersachsen.de/startseite/themen/haushalt/haushaltsplane/nachtragshaushalt_2025_und_haushalt_2026/nachtragshaushalt-2025-und-haushalt-2026-sofortprogramm-zur-starkung-von-investitionen-und-zur-entlastung-der-kommunen-243045.html).**{#par-a2e1ua}
**Press Office of the Senate of the Free Hanseatic City of Bremen (2025), [Senat bringt Nachtragshaushalte 2025 auf den Weg. Landesregierung unterstützt mit Neuverschuldung beide Kommunen](https://www.senatspressestelle.bremen.de/pressemitteilungen/senat-bringt-nachtragshaushalte-2025-auf-den-weg-476220), press release of 28 October 2025.**{#par-i8uiii}
1. **{#_ftn_root_1} This chapter relates to data from the national accounts and Maastricht debt. It is followed by reporting on budgetary developments (government finance statistics) and budget planning.**
{#par-u8i526}
2. **{#_ftn_root_2} For more information on the allocation of debt shares, see Deutsche Bundesbank (2025a), Chapter 2.2 "[Germany's share in the debt of EU institutions in 2024](https://publikationen.bundesbank.de/publikationen-en/reports-studies/monthly-reports/monthly-report-april-2025-954672?article=commentaries-economic-conditions-and-public-finances-954658#2.2-Germany-s-share-in-the-debt-of-EU-institutions-in-2024)".**
{#par-u1i874}
3. **{#_ftn_root_3} See Deutsche Bundesbank (2026), Deutsche Bundesbank (2025c), Supplementary information: Stability-oriented adaptation of relaxed debt brake, section 2.1 "[Monthly Report -- May 2025](https://publikationen.bundesbank.de/content/957960)", Chapter 3 of this report, "[Central government finances](#3-Central-government-finances)", and Deutsche Bundesbank (2025d).**
{#par-ieao24}
4. **{#_ftn_root_4} For more information, see Deutsche Bundesbank (2025e).**
{#par-eo6763}
5. **{#_ftn_root_5} For 2025, this article reports on tax revenue excluding pure local government taxes, as no data on these are yet available for the fourth quarter. For 2026, the data refer to revenue including pure local government taxes. These taxes have only a minimal impact on developments.**
{#par-i21a46}
6. **{#_ftn_root_6} Changes in wages, employment, corporate profits and private consumption.**
{#par-i35o25}
7. **{#_ftn_root_7} For more details, see Deutsche Bundesbank (2025b), Chapter 2 "[Tax revenue](https://publikationen.bundesbank.de/publikationen-en/reports-studies/monthly-reports/monthly-report-november-2025-970814?article=public-finances-970796#2-Tax-revenue)".**
{#par-ea2eoa}
8. **{#_ftn_root_8} Information on the fourth quarter of 2025 is still lacking for local business tax.**
{#par-i3eo7o}
9. **{#_ftn_root_9} See Deutsche Bundesbank (2025b).**
{#par-i2aa26}
10. **{#_ftn_root_10} These repayments are recorded in a different way in some of central government's reports. Ultimately, they do not create any budgetary leeway: central government financed this aid with emergency borrowing, and must therefore use the repayments to settle the debt. Central government therefore counts an equal amount of additional net borrowing towards repayments. As a result, these repayments do not change the net borrowing reported by central government on balance. In the 2024 budget accounts, the repayments no longer impacted the budget balance either (see [Federal Ministry of Finance](https://www.bundeshaushalt.de/static/daten/2024/ist/Haushaltsrechnung_2024_Band_1_webg.pdf) (2025a), p. 4 and p. 9). In the Bundesbank's budgetary analysis, by contrast, the repayments reduce net borrowing (Table 5.3, item 2.c) and improve the budget balance (Table 5.3, item 1.a). In order to correctly reflect the debt brake requirements, the necessary repayments have thus been deducted from the structural borrowing limit of 0.35 % of (see Table 5.3, item 2.h).**
{#par-e5u99o}
11. **{#_ftn_root_11} Data as at January 2026; provisional settlement with updated in March 2026. See [Federal Ministry of Finance](https://www.bundesfinanzministerium.de/Content/DE/Downloads/Broschueren_Bestellservice/Monatsberichte/2026/monatsbericht-2026-01.pdf?__blob=publicationFile&v=5) (2026).**
{#par-ei1456}
12. **{#_ftn_root_12} The Federal Ministry of Finance did not report the result in the provisional settlement, but it can be calculated on the basis of available figures.**
{#par-ae9546}
13. **{#_ftn_root_13} For more details on this recommendation, see Deutsche Bundesbank (2026), specifically Chapter 3.1.3 "[Government investment: gear new scope for borrowing towards infrastructure](https://publikationen.bundesbank.de/content/972822)".**
{#par-e8135a}
14. **{#_ftn_root_14} In order to fully assess last year's developments, further data on investment expenditure covered by the exemption for defence spending (Table 5.3, item 4.a4-n -- deducted due to being financed by other debt) and by the Infrastructure and Climate Neutrality Fund are required. However, these additional details would not materially alter the picture.**
{#par-o813i8}
15. **{#_ftn_root_15} From a budgetary perspective, expenditure is not the only relevant factor when it comes to the sectoral exemption. Revenue arising in the defence sector and mainly generated from (debt-financed) expenditure for the year in question also plays a role. The estimated revenue of almost €1 billion stemming from adjustments to the payment plan for clothing has a similar effect: payments already made are booked back here as revenue. Afterwards, they can be financed by borrowing under the sectoral exemption. When ascertaining scope for borrowing, the Federal Ministry of Finance only deducts revenue which, per the accompanying note to the estimates, increases spending authorisations (slightly less than €½ billion). This approach -- purely based on budget implementation rules -- ultimately expands the scope for borrowing under the sectoral exemption by almost another €1½ billion in 2025 compared with the broader approach described earlier in this footnote.**
{#par-o9u379}
16. **{#_ftn_root_16} Only the entities for which central government publishes monthly cash data are included. As such, infrastructure and regional transport branches of Deutsche Bahn , Autobahn , the bad bank FMS Wertmanagement and the German Nuclear Waste Disposal Financing Fund, in particular, are not commented upon.**
{#par-uo95ui}
17. **{#_ftn_root_17} As the central government budget does not contain borrowing plan figures for some of the off-budget entities with a surplus (such as the Economic Stabilisation Fund and pension funds), the total notional increase is as much as €72 billion.**
{#par-u1o476}
18. **{#_ftn_root_18} No meaningful data on the annual result are yet available for the federal states due to the absence of fourth quarter data for off-budget entities. Information on debt brake settlement is also still outstanding. It would be helpful if state governments could publish provisional figures on their most important off-budget entities and their debt brakes as quickly as central government and, ideally, by a uniform reporting date.**
{#par-u88679}
19. **{#_ftn_root_19} See Federal Ministry of Finance (2025b). In 2025, Berlin, Brandenburg, Bremen, Hamburg, Hesse, Lower Saxony and Schleswig-Holstein already made use of this option.**
{#par-o541ue}
20. **{#_ftn_root_20} The calculation of cyclical components and the classification of financial transactions vary from state to state and are difficult to grasp overall. Transparent and clear data on state government reserves are not available. See Deutsche Bundesbank (2025e), [Monthly Report -- October 2025](https://publikationen.bundesbank.de/content/967186) "[Monthly Report -- October 2025](https://publikationen.bundesbank.de/content/967186)" for information on 2024 as an example.**
{#par-o9e442}
21. **{#_ftn_root_21} See Federal Ministry of Finance (2025b). In addition to the states mentioned in footnote 19, Mecklenburg-West Pomerania, North Rhine-Westphalia, Saarland and Thuringia are expected to make use of the structural borrowing option in 2026.**
{#par-a3ia79}
22. **{#_ftn_root_22} Hesse, Bremen and Lower Saxony, for example, intend to pass on some of the funds obtained via the new borrowing option to their local governments (see Ministry of Finance for Hesse (2025), Press Office of the Senate of the Free Hanseatic City of Bremen (2025), Ministry of Finance for Lower Saxony (2025)).**
{#par-ee16i5}
23. **{#_ftn_root_23} The final figures for 2025 are not yet available.**
{#par-e48985}
24. **{#_ftn_root_24} The pension insurance scheme pays one-half of pension recipients' contributions to the statutory health insurance scheme. The higher supplementary contribution rates resulted in additional expenditure of just over €1½ billion for the pension insurance scheme.**
{#par-eoa221}
25. **{#_ftn_root_25} See Federal Ministry of Labour and Social Affairs (2025).**
{#par-o9447u}
26. **{#_ftn_root_26} Central government will reimburse the additional expenditure caused by the stabilisation of the replacement rate at 48 % up to 2031 and by the consequently higher replacement rates thereafter. See Deutsche Bundesbank (2025b), Chapter 5.1.2 "[Monthly Report -- November 2025](https://publikationen.bundesbank.de/content/970814)".**
{#par-ia5949}
27. **{#_ftn_root_27} For information on longer-term simulations, see Deutsche Bundesbank (2023), pp. 75‑82.**
{#par-u551uu}
28. **{#_ftn_root_28} There is a fairly close relationship between the minimum ages for retiring early on a full pension and the statutory retirement age, on the one hand, and the age at which insurees actually retire, on the other. See also Deutsche Bundesbank (2025f), in Chapter 1 "[Monthly Report -- June 2025](https://publikationen.bundesbank.de/content/958724)".**
{#par-u867iu}
29. **{#_ftn_root_29} In the core budget, i.e. excluding the Federal Employment Agency's civil servants' pension fund. The transfers to this fund come out of the core budget. The civil servants' pension fund recorded a surplus of €½ billion. At the end of 2025, its balance amounted to just over €8½ billion.**
{#par-ea7318}
30. **{#_ftn_root_30} The insolvency benefit and winter employment assistance reserves were up to €2½ billion at the end of the year.**
{#par-u5ui83}
31. **{#_ftn_root_31} The Federal Employment Agency's revenue from the loan is not recognised as a deficit-reducing item. For central government, by contrast, the loan is recorded as a financial transaction, increasing expenditure.**
{#par-u6i662}
32. **{#_ftn_root_32} See Deutsche Bundesbank (2025g).**
{#par-e21ae9}
*[**NATO**]: North Atlantic Treaty Organization
*[SVIK]: Special fund for infrastructure and climate neutrality
*[Q4]: fourth quarter
*[AG]: Aktiengesellschaft
*[VAT]: value added tax
*[**GDP**]: gross domestic product
*[NATO]: North Atlantic Treaty Organization
*[NGEU]: NextGenerationEU
*[GmbH]: Gesellschaft mit beschränkter Haftung
*[EU]: European Union
*[COVID]: coronavirus disease
*[GDP]: gross domestic product
*[**NGEU**]: European Union
*[**SoFFin**]: Sonderfonds Finanzmarktstabilisierung
*[KTF]: Klima- und Transformationsfonds